Insurance , Advertising , SEO
Business insurance. Local business connections. Free DealMaker readers.
St. Louis, Missouri

-
Amerishop Services | Store
Online Store and Business Directory
All Advertising Directories are a LEASE
Search this site
2040 results found with an empty search
- Fire Damage Restoration & Cleanup Services Jefferson City MO: Find a Trusted Local Pro
Focus Keyword: fire-damage-restoration-jefferson-city-mo URL Slug: fire-damage-restoration-jefferson-city-mo-65101 Category: Fire Damage Restoration | Jefferson City MO Excerpt: A practical guide to fire damage restoration in Jefferson City, MO 65101, including emergency board-up, smoke and soot removal, contents cleaning, insurance documentation, and local provider verification. SEO Title: Fire Damage Restoration & Cleanup Services Jefferson City MO: Find a Trusted Local ProAmerishop Services LLC SEO Advertisinghttps://cdn.marblism.com/Txa45EumT5_.webp SEO Description: Amerishop Services LLC SEO Advertising A practical Jefferson City, MO 65101 guide to emergency fire cleanup, smoke and soot removal, insurance documentation, and choosing a local restoration provider.https://cdn.marblism.com/Txa45EumT5_.webp og:site_name: Amerishop Services LLC SEO Advertising og:image:https://cdn.marblism.com/Txa45EumT5_.webp og:image:width: 1200 og:image:height: 630 Featured Image Alt Text: Fire-damaged home in Jefferson City Missouri prepared for professional fire damage restoration and cleanup Publishing Note: Draft for manual transfer to amerishop.biz through the Emergent platform. Do not publish on Wix. Hashtags: #FireDamageRestoration #FireDamageRestorationJeffersonCityMO #JeffersonCityMO #ColeCountyMO #65101 #MidMissouri #SmokeDamageCleanup #SootRemoval #FireCleanup #HomeFireProtection #InsuranceClaims #HomeInsuranceMissouri #RestorationServices #EmergencyBoardUp #RoofTarping #OdorRemoval #ContentsRestoration #WaterDamageMitigation #PropertyRestoration #LocalBusinessDirectory #AmerishopBiz #DependableBrokers #RandyDinwiddie #JeffersonCityHomes #ColeCountyHomes #MissouriHomeowners #FireSafetyTips #ReplacementCost #AdditionalLivingExpenses #TrustedLocalPro Search Terms: fire damage restoration Jefferson City MO fire cleanup services 65101 smoke damage restoration Cole County soot removal Jefferson City Missouri emergency board-up Jefferson City MO roof tarping after house fire Missouri home fire restoration near Jefferson City fire damage insurance claim Missouri contents restoration Jefferson City MO commercial fire cleanup Cole County trusted local fire restoration company home fire protection Mid-Missouri 314-580-3455 | fire-damage-restoration-jefferson-city-mo | Dependable Brokers A fire can damage far more than the room where the flames began. Smoke residue can move through HVAC systems, firefighting water can soak floors and insulation, and heat can weaken materials that appear intact. If your home or business is in Jefferson City, Cole County, or the 65101 area, the right response is organized, documented, and fast. That is why searching for fire-damage-restoration-jefferson-city-mo should involve more than choosing the first company that answers the phone. Do you know whether the provider offers emergency board-up, water extraction, contents cleaning, odor treatment, and reconstruction? Will the company provide itemized documentation for your insurance claim? Can the team explain what happens next without pressuring you into unnecessary work? This Amerishop directory and SEO guide is designed to help you compare local options and make a more informed decision. Choice: Select a restoration provider based on documented services, response capability, insurance communication, and local service coverage: not just a search ranking. 314-580-3455 | fire-damage-restoration-jefferson-city-mo | Dependable Brokers Start With Safety and Property Stabilization Do not re-enter a fire-damaged property until the fire department or other authorized officials confirm that it is safe. Electrical hazards, unstable ceilings, damaged gas lines, hidden hot spots, and contaminated materials can create serious risks after the flames are gone. A professional restoration company will generally begin with an assessment and emergency stabilization. Common first steps include: Inspecting visible fire, smoke, soot, and water damage Photographing affected areas for the claim file Boarding up broken windows, doors, and other openings Installing a roof tarp when the roof is compromised Removing standing water from firefighting efforts Using air movers and dehumidifiers to limit secondary water damage Identifying areas that require structural evaluation Separating salvageable contents from items requiring disposal or specialized cleaning The purpose of emergency mitigation is not to make the property look finished overnight. It is to prevent additional damage while the scope of restoration is being determined. Advantage: Prompt stabilization can reduce exposure to rain, animals, unauthorized entry, mold growth, and additional deterioration. Ask how quickly the provider can reach your property in Jefferson City or elsewhere in Cole County. 314-580-3455 | fire-damage-restoration-jefferson-city-mo | Dependable Brokers Understand What Fire Damage Cleanup Includes Fire restoration is a multi-stage process. A provider that only removes debris may not be equipped to handle smoke odor, structural repairs, contents restoration, or insurance documentation. A full-service scope may include: Smoke and soot removal: Soot can be acidic and may continue damaging metals, painted surfaces, cabinetry, and fabrics if left untreated. Odor control: Smoke odor can remain in drywall, insulation, flooring, upholstery, and ductwork. Professional deodorization may involve HEPA filtration, specialized cleaning agents, thermal fogging, or other techniques selected for the property. Water damage mitigation: Water used to extinguish a fire can create a second loss. Extraction and structural drying should be addressed promptly. Contents cleaning: Furniture, clothing, appliances, electronics, documents, and family keepsakes may be cleaned, packed out, stored, or evaluated for replacement. Structural reconstruction: Damaged drywall, framing, flooring, roofing, cabinetry, paint, and trim may require repair or replacement. Final inspection: The restoration team should review completed work with you and identify any remaining concerns. The SERVPRO of Jefferson City fire damage service page provides a useful example of a typical service scope. Its listed services include board-up and roof tarping, water removal and drying, soot and odor removal, contents cleaning, and commercial fire cleanup. The company lists a 24/7 emergency number at (573) 635-5883 and identifies Jefferson City and surrounding communities within its service area. Choice: Before authorizing work, request a written scope that separates emergency mitigation, cleaning, contents handling, and reconstruction. 314-580-3455 | fire-damage-restoration-jefferson-city-mo | Dependable Brokers Compare Local Restoration Providers Carefully Several companies advertise fire damage restoration and cleanup services in Jefferson City, Columbia, and surrounding Mid-Missouri communities. Availability, pricing, licensing, insurance, staffing, and actual service coverage can change, so confirm current details directly. Local options identified through available provider information include: SERVPRO of Jefferson City: Lists residential and commercial fire cleanup, emergency response, board-up, water removal, soot cleaning, odor removal, and contents restoration. Phone: (573) 635-5883. ServiceMaster Restoration Services by Aerodry: Lists fire and smoke damage assessment, board-up, roof tarping, water removal, soot cleaning, deodorization, contents cleaning, repairs, and final inspection. The provider’s published service information identifies a Jefferson City-area response number of (573) 282-6357. Rainbow Restoration of Jefferson City: Lists fire and smoke restoration, odor removal, water damage services, and mold remediation. Confirm the current phone number and service area before scheduling because directory listings may show different contact information. River’s Edge: Describes fire restoration services for the Columbia and Jefferson City area, including structural repair, smoke and soot removal, odor control, firefighting-water mitigation, flooring, cabinetry, and painting. 911 Restoration of Central Missouri: Lists emergency fire and smoke restoration, thermal fogging, ozone odor treatment, structural repair, pack-out, and reconstruction. Its published contact number is (573) 892-8845. ABC Environmental Contracting Services: Lists fire damage restoration, water damage, mold remediation, and reconstruction services for Columbia and Jefferson City. You can also review the Better Business Bureau’s fire and water damage restoration category for Missouri as one part of your screening process. Check complaints, business history, insurance, written warranties, and customer feedback: but do not rely on one rating alone. Advantage: A mobile-friendly directory listing gives you a starting point. Your final decision should follow a direct conversation, written estimate, and verification of credentials. 314-580-3455 | fire-damage-restoration-jefferson-city-mo | Dependable Brokers Document the Loss Before the Cleanup Begins Contact your insurance carrier promptly and ask for a claim number. If the home is uninhabitable, ask about Coverage D, commonly called loss-of-use or Additional Living Expense coverage. Depending on the policy, eligible expenses may include temporary housing, increased meal costs, storage, and certain transportation or pet-boarding expenses. Before discarding damaged property, photograph and video each room and item when it is safe to do so. Create a contents inventory with: Item description Brand and model Serial number, when available Approximate purchase date Estimated replacement cost Receipts or photographs Location in the home Your policy may settle personal property using Actual Cash Value (ACV) or Replacement Cost Value (RCV). ACV generally reflects depreciation, while RCV is intended to cover the cost of replacing an item with one of like kind and quality, subject to policy terms and limits. For example, a $300,000 dwelling limit is a policy limit: not an automatic guarantee that every rebuilding expense will be paid. Ask whether your coverage includes extended replacement cost, ordinance-or-law coverage, debris removal, matching materials, and adequate ALE limits. Some policies offer extended replacement cost endorsements of 25% or 50% above the base dwelling limit, but availability and conditions vary. Dependable Brokers provides home fire insurance information for Missouri homeowners, including dwelling coverage, personal property, smoke damage, loss of use, and replacement cost considerations. You can also review its Missouri wildfire and fire damage protection guide. Choice: You have the right to ask what your policy covers, what documentation is required, and whether a proposed restoration scope matches the documented damage. A restoration contractor can help organize records, but your insurer determines coverage under the policy. 314-580-3455 | fire-damage-restoration-jefferson-city-mo | Dependable Brokers Reduce Future Fire Risk in Your Home Restoration addresses the current loss. Prevention helps protect your next chapter. Jefferson City and Cole County homeowners should review basic fire protection measures regularly: Install smoke alarms on every level, inside sleeping areas, and immediately outside sleeping areas. Test alarms monthly and generally replace units every 10 years, following manufacturer instructions. Keep an ABC fire extinguisher in the kitchen and near mechanical or utility areas. Clean dryer lint filters after every use and arrange periodic vent cleaning. Keep space heaters, fireplaces, and other heat sources away from curtains, furniture, and stored materials. Avoid overloaded outlets and damaged extension cords. Keep hallways, stairways, doors, and bedroom egress windows clear. Maintain defensible space by removing dry leaves, dead vegetation, and debris near the structure. Ask a qualified professional to inspect chimneys, heating systems, and questionable electrical work. Local building and fire requirements can vary. For reconstruction, ask whether permits, inspections, code-compliant materials, and ordinance-or-law coverage will affect the project. Advantage: A current home inventory, properly sized insurance policy, working smoke alarms, and a preselected emergency contact can save valuable time when every minute matters. 314-580-3455 | fire-damage-restoration-jefferson-city-mo | Dependable Brokers Make Your Next Call With Confidence If you need fire-damage-restoration-jefferson-city-mo services now, focus first on safety, emergency stabilization, and documentation. Ask each provider: Do you offer 24/7 emergency response in ZIP code 65101? Do you handle smoke, soot, odor, and firefighting-water damage? Can you provide a written scope and itemized estimate? Do you offer contents pack-out and secure storage? Do you complete reconstruction or coordinate with a qualified builder? What certifications, licenses, and insurance does your company carry? How will you communicate with my insurance adjuster? What work can begin immediately, and what requires approval? Dependable Brokers serves as a Mid-Missouri insurance and business-growth resource, connecting families and business owners with practical coverage guidance and local information. For insurance questions, contact Randy Dinwiddie at 314-580-3455 or visit Dependable Brokers. For a current restoration directory listing, verify availability, response times, credentials, and pricing directly with the provider. A careful comparison can help you protect your property, preserve your claim documentation, and move toward a safer recovery in Jefferson City and Cole County.
- High Value Home Insurance Missouri: Premium Estate & Custom Home Protection
Focus Keyword: high value home insurance missouri chubb URL Slug: high-value-home-insurance-missouri-chubb-65101 Category: Dependable Brokers (Insurance) Excerpt: Explore high value home insurance Missouri Chubb options for custom estates, including premium dwelling limits, extended replacement cost, valuable property protection, liability coverage, and local guidance from Dependable Brokers. SEO Title: High Value Home Insurance Missouri: Premium Estate & Custom Home Protection | Dependable Brokers SEO Description: High value home insurance Missouri Chubb guidance for custom estates, extended replacement cost, valuable property, liability limits, and local support from Dependable Brokers. og:site_name: Dependable Brokers og:image:https://cdn.marblism.com/_v1Pwoe7Ihi.webp og:image:width: 1200 og:image:height: 630 Featured Image Alt Text: Premium custom Missouri estate protected by high value home insurance with a translucent shield and Marblism-style navy, gold, and burnt orange design Visual Direction: Marblism border protocol with high-contrast geometric patterns, detailed Missouri organic elements, navy and royal blue foundations, stark white and black accents, and polished frosted-glass forms. 314-580-3455 | high value home insurance missouri chubb | Dependable Brokers Your custom home is not adequately protected simply because the policy shows a large dollar amount. A premium estate in Jefferson City, Columbia, Cole County, Boone County, or Holts Summit may include custom cabinetry, imported flooring, architectural millwork, high-end appliances, detached structures, landscaped grounds, valuable collections, and substantial liability exposure. That is why high value home insurance Missouri Chubb deserves a detailed coverage review rather than a quick online quote. Chubb’s Masterpiece homeowners program is designed for households with more complex property and asset-protection needs. Dependable Brokers can help you evaluate whether a Chubb option, another premium carrier, or a coordinated insurance plan better fits your property and financial goals. You should be able to ask clear questions, compare coverage honestly, and work with a local point of contact: without a corporate runaround. 314-580-3455 | high value home insurance missouri chubb | Dependable Brokers Premium dwelling limits should reflect rebuilding: not resale value A home’s market value and reconstruction cost are different measurements. Market value may include land, neighborhood demand, and local real estate conditions. Dwelling coverage should instead estimate what it would cost to rebuild the structure with comparable materials, craftsmanship, architectural detail, labor, permits, debris removal, and code-required upgrades. For a custom Missouri home, the correct dwelling limit may be substantially higher than the purchase price or county assessment. A $750,000 dwelling limit, for example, can be insufficient if a regional storm causes labor shortages, material price increases, and increased demand for contractors. Chubb states that its high-value homeowners coverage includes an assessment process designed to help establish an accurate replacement cost. That review may account for: Custom architectural features and specialty finishes Upgraded kitchens, bathrooms, flooring, lighting, and built-ins Detached garages, guest houses, workshops, and pool structures Local labor and material costs in Mid-Missouri Architect, designer, engineering, and debris-removal expenses Building-code upgrades required during reconstruction You can review Chubb’s high value homeowners coverage information and discuss availability with an independent agent. Advantage: A professional reconstruction estimate helps prevent an outdated dwelling limit from becoming a serious financial gap after a covered loss. 573-548-0394 | high value home insurance missouri chubb | Dependable Brokers Extended replacement cost provides a critical layer of protection Many homeowners use the phrase “guaranteed replacement cost” when discussing coverage that responds if rebuilding exceeds the stated dwelling limit. Chubb’s public homeowners information describes this feature as extended replacement cost coverage. After a covered loss, Chubb states that it may pay to repair or rebuild the home to its original condition even when the cost exceeds the policy limit, subject to policy terms and jurisdictional conditions. The coverage may also respond to upgrades required by modern building codes. This distinction matters. You should ask: Is the coverage extended replacement cost or another form of replacement-cost protection? What conditions must you meet to qualify? Is there a stated percentage, an unlimited provision, or another policy limitation? Does the provision apply to the entire dwelling or only specific components? Are special deductibles excluded from any large-loss waiver? Chubb also describes a deductible waiver in most states when the base deductible is $50,000 or less and a covered loss exceeds $100,000. The company notes that terms vary by state and that the waiver may not apply when a special deductible: such as a vacant-home or named-storm deductible: is involved. That is why your Missouri policy should be reviewed based on the actual form and endorsements, not on a sales phrase alone. Choice: Ask for the exact extended replacement cost wording, deductible conditions, and Missouri availability before you make a coverage decision. 314-580-3455 | high value home insurance missouri chubb | Dependable Brokers Protect the contents that make your estate unique Standard homeowners insurance may not be structured for a large collection of jewelry, fine art, wine, antiques, firearms, musical instruments, designer furnishings, or specialty electronics. Policy sublimits can create surprises when valuable property is lost or damaged. A high-value policy review should identify which items need scheduled or valuable articles coverage. Ask whether each item is covered for: Replacement cost or actual cash value Agreed value or another settlement method Worldwide loss protection Mysterious disappearance Professional appraisal requirements Pair-and-set loss Newly acquired items Restoration, conservation, or specialist replacement Chubb’s Missouri Masterpiece discount material states that homeowners may save 10% on the homeowners premium with $25,000 or more in scheduled jewelry coverage, or $50,000 or more in valuable articles coverage, subject to eligibility and policy terms. That does not mean you should schedule items solely to pursue a discount. The coverage must match what you own and what it would cost to replace. A current appraisal and organized digital inventory can make the claims process more efficient. Advantage: Properly scheduled property can provide broader protection and clearer valuation than relying on a standard contents sublimit. 314-580-3455 | high value home insurance missouri chubb | Dependable Brokers Liability limits should protect your broader financial picture Your home is only one part of your exposure. A swimming pool, guest house, domestic employee, rental property, recreational vehicle, youthful driver, or frequent guest activity can increase personal liability concerns. A premium estate review may include: Higher personal liability limits Medical payments coverage Personal excess or umbrella liability insurance Coverage for rental or secondary residences Protection for domestic staff-related exposures Defense costs and settlement conditions Coverage coordination for boats, recreational vehicles, and additional autos Many affluent households consider liability limits of $500,000 or more, paired with a personal umbrella policy. The correct amount depends on your assets, income, activities, property ownership, and risk tolerance. Would a standard liability limit adequately protect your savings, business interests, investment accounts, and future earnings after a serious claim? That question deserves a written coverage analysis. Dependable Brokers also serves small business owners who need commercial protection. If your residence connects to a business operation, review the difference between personal and commercial coverage through the business insurance consultation page. Choice: Coordinate your home, auto, valuable property, and umbrella policies so one uncovered exposure does not undermine the rest of your financial plan. 573-548-0394 | high value home insurance missouri chubb | Dependable Brokers Missouri credits can improve value without reducing protection Chubb’s Missouri discount material lists several possible credits for protective features and policy structure. Eligibility depends on underwriting, documentation, policy form, and current carrier rules. Examples include: 10% for combined homeowners and auto coverage Up to 15% for qualifying protective systems At least 5% for a central station fire alarm 10% for a residential sprinkler system Up to 15% for hail-resistant roof covering 15% for fire-resistive construction Up to 24% for a home 10 years old or less Up to 17% for a home renovated within the previous six years Up to 10% for qualifying claims-free history 2.5% when the home has no mortgage or lien, subject to conditions A water leak detection system, permanently installed backup generator, central station alarm, gated access, or updated roof may improve both risk management and premium efficiency. However, a discount should never be the only reason to install a protective device. The practical benefit is reducing the likelihood or severity of a loss. Advantage: A local review can help you document eligible safety features and compare the real premium impact before you invest in upgrades. 314-580-3455 | high value home insurance missouri chubb | Dependable Brokers Get local guidance without losing access to premium coverage Dependable Brokers serves Mid-Missouri families, property owners, and business owners with local insurance guidance. Randy Dinwiddie can help you organize the information required for a high-value home review, including: Current dwelling limit and policy declarations Recent appraisal or construction documents Roof age and major renovation details Alarm, sprinkler, generator, and water-shutoff information Jewelry, art, and collection appraisals Auto, boat, rental-property, and umbrella coverage Mortgage and ownership details Prior claims and loss history Call 314-580-3455 or 573-548-0394 to request a fast, documentation-based review. If you are in Jefferson City, Columbia, Holts Summit, Cole County, or Boone County, local details can make a meaningful difference in how your risk is evaluated. You can also review Dependable Brokers or learn more about the agency through the About Us page. Final Choice: Choose coverage based on reconstruction cost, policy language, valuable property needs, liability exposure, and service quality: not simply the lowest annual premium. Randy Dinwiddie Licensed agent Holts Summit Mo 65043 Coverage descriptions are general and subject to the terms, conditions, exclusions, limits, endorsements, and availability of the policy issued. Premium examples and discount percentages are not quotes or guarantees. Chubb products may not be available in every situation or jurisdiction. Contact Dependable Brokers for a personalized review. Tags #HighValueHomeInsurance #MissouriHomeInsurance #ChubbMasterpiece #LuxuryHomeInsurance #CustomHomeInsurance #EstateInsurance #ExtendedReplacementCost #GuaranteedReplacementCost #DwellingCoverage #ReplacementCostCoverage #PersonalPropertyInsurance #ValuableArticlesCoverage #JewelryInsurance #FineArtInsurance #PersonalLiabilityInsurance #UmbrellaInsurance #MissouriInsuranceBroker #JeffersonCityHomeInsurance #ColumbiaMOHomeInsurance #ColeCountyInsurance #BooneCountyInsurance #HoltsSummitInsurance #MidMissouriInsurance #HomeInsuranceDiscounts #HailResistantRoof #WaterLeakDetection #FireProtection #HighNetWorthInsurance #CustomEstateProtection #DependableBrokers Search Terms high value home insurance Missouri Chubb Chubb Masterpiece insurance Missouri luxury home insurance Jefferson City MO custom estate insurance Columbia Missouri extended replacement cost home insurance Missouri guaranteed replacement cost insurance Missouri high dwelling limits homeowners insurance Missouri valuable articles insurance Mid-Missouri jewelry coverage Chubb Missouri personal umbrella insurance Cole County custom home insurance Boone County MO Dependable Brokers high value home insurance
- Commercial Property Fire Insurance Missouri: Protecting Mid-Missouri Businesses
SEO Backend Metadata 314-580-3455 | commercial insurance missouri | Dependable Brokers Your business represents years of work, investment, and financial planning. Whether you operate a storefront in Jefferson City, an office in Columbia, a warehouse in Cole County, or a service business near Holts Summit, a serious fire can damage far more than walls and equipment. It can interrupt your revenue, affect payroll, disrupt customer relationships, and create expenses that continue long after the fire department leaves. That is why commercial property fire insurance Missouri business owners can depend on should be structured around the full financial picture: not simply the estimated value of the building. At Dependable Brokers, we help Mid-Missouri business owners review property protection, liability exposure, and business continuity needs. Call 314-580-3455 to discuss your current policy, upcoming purchase, lease requirements, or new business location. Protect your investment before a loss occurs. Commercial property fire insurance is generally included within a broader commercial property policy or business owner’s policy. Coverage depends on the policy form, covered causes of loss, exclusions, deductibles, limits, and endorsements you select. A properly designed policy may address: The commercial building and permanently installed fixtures Furniture, computers, inventory, tools, and equipment Smoke and soot damage following a covered fire Debris removal and certain cleanup expenses Business income lost during a covered shutdown Extra expenses required to continue operating elsewhere Fire legal liability for damage to rented premises Certain wind, hail, vandalism, theft, or water losses, depending on the policy Would your current policy provide enough money to rebuild at today’s construction prices? Would it replace your inventory at its current value? Could your business continue paying rent, payroll, utilities, and loan payments while repairs are underway? Those questions deserve specific answers. Choice Advantage: A coverage review connects your policy limits to the actual value of your building, contents, operations, and financial obligations. 314-580-3455 | commercial insurance missouri | Dependable Brokers Cover the building: and everything that makes it useful. If you own the building, commercial property coverage may protect the structure, permanent fixtures, electrical systems, plumbing, walls, floors, roofing, and certain outdoor property. Replacement cost coverage is often an important consideration because rebuilding a commercial structure may cost significantly more than its prior purchase price. For example, a building purchased years ago for $400,000 might require $650,000 or more to rebuild after a total loss because of labor, materials, architectural, demolition, and code-compliance costs. The correct limit depends on a professional valuation and the property’s construction, square footage, occupancy, location, and features. Business personal property, often called BPP, covers the movable assets used in your operation. Depending on your business, that may include: Retail inventory and merchandise Restaurant appliances, cooking equipment, and refrigeration Manufacturing machinery and tools Computers, servers, printers, and point-of-sale systems Office furniture, fixtures, and supplies Customer property in your care, custody, or control, when applicable If you lease your space, do not assume the landlord’s policy protects your business property. The landlord’s insurance generally addresses the building owner’s interest. Your inventory, equipment, furniture, tenant improvements, and lost income may require your own coverage. Choice Advantage: Owners need building and contents protection. Tenants usually need business personal property, tenant improvements, business income, and appropriate liability coverage. 314-580-3455 | commercial insurance missouri | Dependable Brokers Replacement cost can reduce the depreciation gap. Commercial property policies commonly use either replacement cost or actual cash value. Replacement cost coverage is designed to pay the cost to repair or replace damaged property with materials of similar kind and quality, subject to the policy terms and limit. Actual cash value generally accounts for depreciation. While actual cash value may produce a lower premium, it can also create a substantial shortfall after a major fire. Consider a business with $100,000 in equipment that has depreciated to an actual cash value of $45,000. If the policy pays on an actual cash value basis, the claim payment may be much lower than the cost of purchasing current replacement equipment. Your deductible also matters. A $2,500 deductible, $5,000 deductible, or higher amount changes how much you contribute to a covered loss. Wind and hail deductibles may be separate from the fire deductible, depending on the policy. Ask: Is the building insured to an accurate replacement cost? Are inventory limits high enough during seasonal peaks? Are specialized tools and equipment scheduled correctly? Does the policy apply coinsurance requirements? Is agreed value available for your property? Are recent improvements reflected in the policy? Choice Advantage: The lowest premium is not always the lowest total cost. Compare deductibles, valuation methods, exclusions, and claim limits: not just the monthly payment. 314-580-3455 | commercial insurance missouri | Dependable Brokers Protect revenue while repairs are underway. A fire can stop sales immediately, but many expenses continue. Rent, payroll, utilities, taxes, debt payments, software subscriptions, and vendor obligations may remain due even when customers cannot enter your location. Business income coverage, also called business interruption coverage, may help replace lost income and certain continuing expenses after a covered property loss. Extra expense coverage may help pay additional costs to keep operating, such as: Renting a temporary office or retail location Moving inventory to another facility Leasing temporary equipment Paying expedited shipping charges Increasing advertising to notify customers of a new location Making temporary improvements to continue serving clients The coverage period is important. Some policies use a defined period of restoration, while others may include an extended business income period after operations resume. Your limit should reflect realistic recovery time: not simply the time needed to remove debris. A professional service business may reopen in a matter of weeks. A restaurant, warehouse, manufacturer, or specialized retailer may require months to repair, replace equipment, obtain permits, restock inventory, and rebuild its customer base. Choice Advantage: Property coverage helps repair physical damage. Business income and extra expense coverage help protect the revenue and stability that keep your business alive during recovery. 314-580-3455 | commercial insurance missouri | Dependable Brokers Account for Missouri weather and policy exclusions. Fire is not the only major property risk in Mid-Missouri. Columbia, Jefferson City, Boone County, and Cole County businesses also face severe thunderstorms, wind, hail, tornadoes, frozen pipes, equipment failures, and potential flood exposure. Flood is commonly excluded from standard commercial property policies. If your property is near a creek, river, drainage area, or flood-prone location, ask whether separate flood coverage is appropriate. Equipment breakdown coverage may also be important for boilers, HVAC systems, refrigeration, electrical panels, and machinery that can fail without a traditional fire. Other coverage decisions may include: Ordinance or law coverage: Helps address demolition and increased costs caused by current building-code requirements. Equipment breakdown: May respond to sudden mechanical or electrical failures subject to policy terms. Debris removal: Helps with certain costs to remove damaged materials after a covered loss. Fire legal liability: May protect a tenant if legally liable for fire damage to rented premises. Extra expense: Helps fund temporary measures that keep the business operating. Inland marine coverage: May protect tools, equipment, or property transported away from the primary location. The Missouri FAIR Plan explains that it is a last-resort mechanism for applicants unable to secure basic property insurance through the normal market. It is not intended to replace a comprehensive voluntary commercial policy. You can review the Missouri FAIR Plan for official information. Choice Advantage: A commercial insurance review should examine fire, storm, flood, equipment, liability, and business interruption exposures together. 314-580-3455 | commercial insurance missouri | Dependable Brokers Understand realistic commercial insurance pricing. Commercial insurance pricing varies significantly. Building construction, occupancy, protection class, square footage, roof age, fire protection systems, claims history, location, business operations, limits, and deductibles all influence the premium. For planning purposes, publicly reported ranges for small and mid-sized Missouri businesses may fall near $83 to $250 per month, but actual pricing can be higher or lower. Illustrative annual ranges may include: Low-risk professional office: approximately $350 to $1,200 per year Moderate retail or light warehouse: approximately $800 to $2,500 per year Higher-risk restaurant, manufacturing, or high-inventory operation: approximately $1,500 to $6,000 or more per year These are not quotes or guarantees. A restaurant with commercial cooking equipment, a warehouse storing combustible inventory, and a professional office have very different underwriting profiles. At Dependable Brokers’ business insurance consultation page, you can begin a practical review of your business property and liability needs. For a quick-turnaround discussion, call 314-580-3455 and ask for Randy Dinwiddie. Choice Advantage: Honest pricing starts with accurate information. The right policy balances protection, deductibles, exclusions, and your available budget. 314-580-3455 | commercial insurance missouri | Dependable Brokers Take action before your next renewal. Review your commercial property fire insurance Missouri coverage before a lender, landlord, storm, fire, or claim forces the issue. Gather your building details, lease or loan requirements, equipment list, inventory estimates, recent improvements, payroll information, and business income figures. Then ask whether your coverage reflects the way your business operates today. Dependable Brokers serves Mid-Missouri families and businesses in Jefferson City, Columbia, Cole County, Boone County, Holts Summit, and surrounding communities. Randy Dinwiddie can help you identify coverage gaps, compare available options, and organize a plan designed around your financial goals. Call 314-580-3455 for a prompt commercial insurance review. Randy Dinwiddie Licensed agent Holts Summit Mo 65043
- DealMaker Motors Jefferson City MO: Dealer-Free Private Party Trucks under $12,000
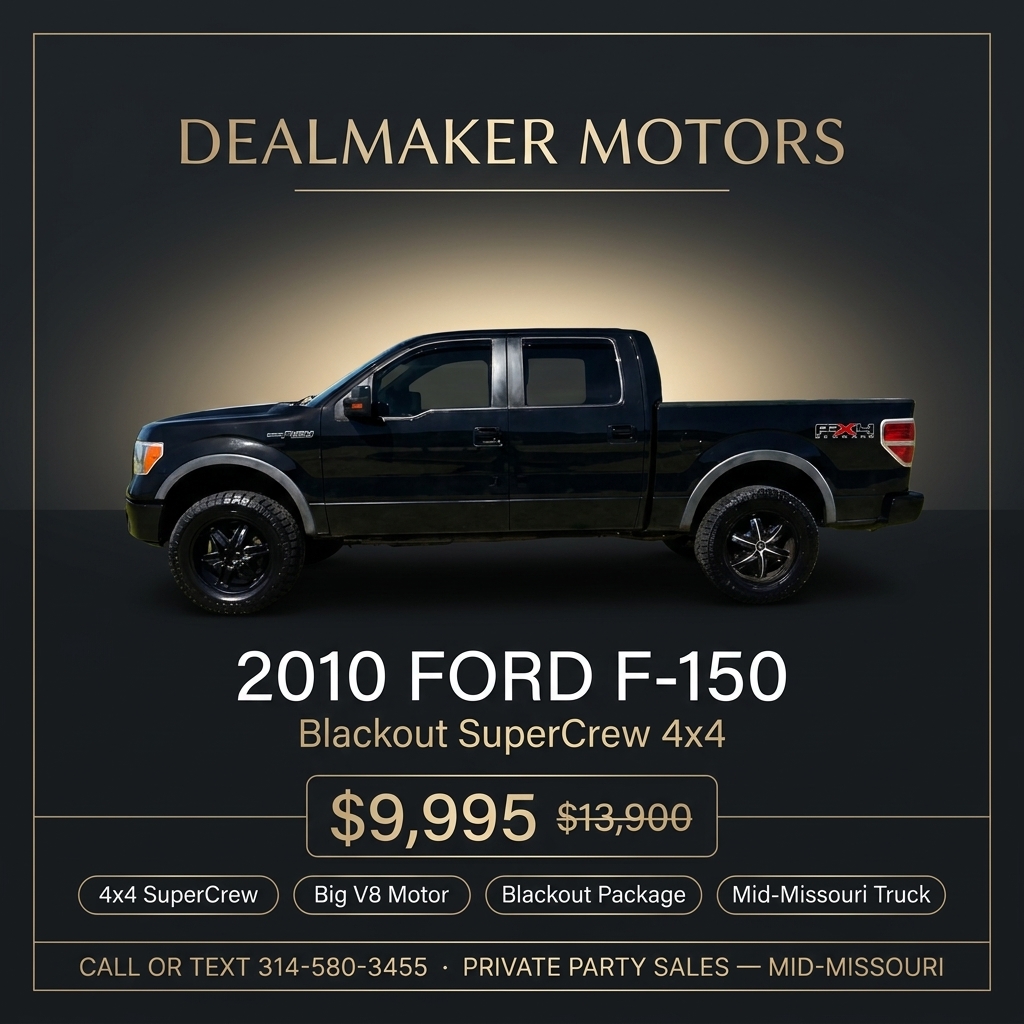
Focus Keyword: private party trucks under $12,000 Jefferson City MO URL Slug: private-party-trucks-under-12000-jefferson-city-mo-65109 Category: Private Party Auto Listings Target ZIP Codes: 65109, 65201 Target Counties: Cole County and Boone County Excerpt: Review a verified 2010 Ford F-150 Blackout SuperCrew 4x4 priced at $9,995 through DealMaker Motors in Jefferson City, MO. See real photos, key features, private-party pricing, inspection guidance, and Missouri title requirements. SEO Title: DealMaker Motors Jefferson City MO: Dealer-Free Private Party Trucks under $12,000 https://static.prod-images.emergentagent.com/jobs/cd1f68a8-7def-4c58-8a0b-02d1733bca66/images/c6742005e3a255a39f3cb6135ef2477ffed87ff9be21ab3d58d595521e636f6e.jpeg SEO Description: DealMaker Motors Jefferson City MO: Review a 2010 Ford F-150 Blackout SuperCrew 4x4 priced at $9,995, with no dealer fees and appointment-based inspection in Mid-Missouri. https://static.prod-images.emergentagent.com/jobs/cd1f68a8-7def-4c58-8a0b-02d1733bca66/images/c6742005e3a255a39f3cb6135ef2477ffed87ff9be21ab3d58d595521e636f6e.jpeg og:site_name: DealMaker Motors og:image:https://static.prod-images.emergentagent.com/jobs/cd1f68a8-7def-4c58-8a0b-02d1733bca66/images/c6742005e3a255a39f3cb6135ef2477ffed87ff9be21ab3d58d595521e636f6e.jpeg og:image:width: 1200 og:image:height: 630 Featured Image Alt Text: Real 2010 Ford F-150 Blackout SuperCrew 4x4 for $9,995 in Jefferson City MO Tags: DealMaker Motors, private party trucks, used Ford F-150, Jefferson City MO, Columbia MO, Cole County, Boone County, 65109, 65201, Mid-Missouri trucks, dealer-free vehicle listings, no dealer fees, 2010 Ford F-150, SuperCrew 4x4, Blackout package, trucks under $12,000, trucks under $10,000, affordable used trucks, private seller vehicles, Missouri auto listings, as-is where-is, used trucks Jefferson City, used trucks Columbia, local vehicle inspection, Missouri title transfer, Missouri sales tax, buyer pays tax and title, DealMaker Motors inventory, DO-AUTO-01, Randy Dinwiddie, 314-580-3455 Search Terms: “private party trucks under $12,000 Jefferson City MO” “used Ford F-150 Jefferson City MO” “dealer-free trucks 65109” “private party trucks 65201” “used trucks Cole County MO” “used trucks Boone County MO” “2010 Ford F-150 Blackout SuperCrew 4x4” “Ford F-150 under $10,000 Missouri” “no dealer fee trucks Mid-Missouri” “buy used truck private party Jefferson City” “used trucks near Columbia MO” “DealMaker Motors truck listings” Hashtags: #DealMakerMotors #JeffersonCityMO #ColumbiaMO #ColeCounty #BooneCounty #65109 #65201 #PrivatePartyTrucks #UsedTrucksMO #FordF150 #F150ForSale #TruckUnder12000 #NoDealerFees #MidMissouri #JeffCityTrucks #ColumbiaMOTrucks #MissouriCars #TruckShopping #AsIsWhereIs #UsedFord #SuperCrew #4x4Truck #AffordableTrucks #BuyPrivateParty #LocalAutoListings #CapitalCityCars #MissouriTruckBuyer #TruckListing #JeffersonCityCars #MidMoAutoSales 314-580-3455 | Private Party Trucks Under $12,000 Jefferson City MO | DealMaker Motors Price up front: $9,995. DealMaker Motors is listing a 2010 Ford F-150 Blackout SuperCrew 4x4 in Jefferson City, Missouri. The listing identifies this truck as a verified private-party vehicle with a big V8 motor, 4x4 capability, SuperCrew cab, and Blackout package. It is listed through the DealMaker Motors inventory page under SKU DO-AUTO-01. This is a practical option for a buyer searching for private party trucks under $12,000 Jefferson City MO, especially if you need four-wheel-drive utility without moving into the $20,000-plus used truck market. The real listing photo appears above so you can begin with the actual vehicle rather than a stock image. DealMaker Motors is not presenting this as a franchise dealership transaction. The listed price is not increased by dealer fees, documentation fees, or middleman markup. You remain responsible for your own Missouri sales tax, title, registration, and related license-office charges. Choice: A $9,995 private-party F-150 gives you a clear starting price, but you should still budget separately for tax, title, registration, inspection, insurance, and any repairs you identify before purchase. 314-580-3455 | 2010 Ford F-150 Blackout SuperCrew 4x4 | DealMaker Motors The truck’s listed configuration is focused on utility: Year: 2010 Make and model: Ford F-150 Configuration: Blackout SuperCrew 4x4 Engine description: Big V8 motor Vehicle type: Pickup truck Listing price: $9,995 Location: Jefferson City, Missouri Seller format: Verified private-party listing Appointment contact: Randy Dinwiddie at (314) 580-3455 Listing status: As-is, where-is A SuperCrew cab provides four full-size doors and additional interior space compared with a regular-cab pickup. The 4x4 system may be useful for rural roads, winter conditions, property maintenance, towing-related tasks, and work around Cole County. However, equipment and mechanical condition should be confirmed in person because the vehicle is sold as-is. What matters most to your budget: a lower acquisition price, newer model year, lower mileage, or a truck already reconditioned by a dealer? There is no universal answer. A private-party truck may reduce transaction fees, but it also places greater responsibility on you to inspect the vehicle and evaluate future maintenance. Advantage: The listing provides a real vehicle photo, an identified configuration, a published price, and an appointment process before you commit. 314-580-3455 | Jefferson City 65109 and Columbia 65201 Truck Buyers | DealMaker Motors This listing is designed for buyers in Jefferson City, Columbia, Cole County, and Boone County. Jefferson City ZIP code 65109 shoppers can arrange an appointment locally, while Columbia ZIP code 65201 shoppers can contact the seller to coordinate viewing details before traveling. The Mid-Missouri service area also makes this listing relevant to buyers coming from Fulton, Holts Summit, Ashland, and nearby communities. If you are comparing used trucks in Jefferson City against used trucks in Columbia, ask the same questions of every seller: Is the advertised price the actual purchase price? Are dealer, documentation, preparation, or advertising fees added later? Can you inspect the truck before payment? Is the title available and properly assignable? What taxes and registration costs will you pay separately? Can you bring a mechanic or trusted vehicle specialist? Texting before you drive from Columbia or another Boone County community can help confirm that the truck remains available and that the appointment location is correct. Serious buyers can generally request a viewing within a day or two, subject to seller availability. Choice: Buyers near 65109 may have the convenience of a Jefferson City appointment, while 65201 shoppers should confirm location and availability before making the trip. 314-580-3455 | Used Ford F-150 Inspection Checklist | DealMaker Motors An as-is private-party sale requires a careful inspection. Bring a trusted mechanic if possible, and do not rely on the listing price alone to determine value. Before money changes hands, examine: Cold-start behavior and engine noise Transmission engagement and shifting Four-wheel-drive operation Brake pedal feel and brake-system condition Tire tread depth and uneven wear Rust, frame damage, leaks, and prior collision evidence Dashboard warning lights Air conditioning, heating, windows, locks, and lights Bed condition, tailgate operation, and towing equipment Title status, lien information, and odometer disclosure Ask for a test drive that includes local streets and highway speeds. Listen for drivetrain vibration, steering play, suspension noise, or braking problems. A pre-purchase inspection is especially important when a vehicle is sold without a warranty. The listing states that the buyer can inspect the truck before purchase and encourages bringing a mechanic or trusted friend. That approach protects your decision-making without turning the transaction into a high-pressure purchase. Advantage: You control the inspection process and can make your offer or purchase decision based on the truck’s observed condition. 314-580-3455 | Missouri Tax, Title, and Registration Requirements | DealMaker Motors In a Missouri private-party vehicle purchase, the seller does not collect your vehicle sales tax. You generally take the assigned title and bill of sale to a Missouri Department of Revenue license office. The Missouri Department of Revenue identifies a 30-day deadline for applying for title and paying applicable sales tax after purchase. The state motor-vehicle sales-tax rate is generally 4.225%, with local sales tax added according to the buyer’s location. The final amount depends on your residence and the transaction details. You should also budget for: Missouri state and local sales tax Title fee Title processing fee Registration fee Plate or plate-transfer charges Proof of insurance Any required inspection documentation Review the official Missouri DOR vehicle titling and registration guidance and use the Missouri motor-vehicle tax calculator to estimate your costs. The exact amount can vary, so do not assume that the $9,995 listing price is your complete out-the-door cost. Choice: The private-party price is $9,995, while your total purchase budget should include Missouri tax, title, registration, insurance, inspection, and any immediate service needs. 314-580-3455 | Schedule a Jefferson City Truck Appointment | DealMaker Motors If this Ford F-150 fits your budget and intended use, text Randy Dinwiddie at (314) 580-3455. Include your name, whether you are coming from Jefferson City or Columbia, and your preferred appointment window. Before arriving, confirm: The truck is still available The $9,995 price remains current The appointment location Payment method accepted Whether a mechanic may inspect the truck Which title and bill-of-sale documents will be provided You can also review the broader DealMaker Motors used vehicle inventory for additional cars, trucks, and SUVs. For broader company information, visit Dependable Brokers. A private-party purchase can be a sensible way to compare used trucks in Cole County and Boone County when you understand the tradeoff: fewer added transaction fees, but more responsibility for inspection and due diligence. Advantage: A quick text can help you confirm availability and arrange a viewing without spending time traveling to an unavailable vehicle.
- Boat Insurance Lake of the Ozarks Missouri: Marina Slip Liability & On-Water Protection
Focus Keyword: boat insurance lake of the ozarks missouri URL Slug: boat-insurance-lake-of-the-ozarks-missouri-65049 Category: Dependable Brokers (Insurance) Excerpt: Learn how boat insurance works at Lake of the Ozarks, including marina slip liability requirements, protection for pontoons, bass boats, and cruisers, fuel-spill coverage, wreckage removal, towing, and local brokerage guidance. SEO Title: Boat Insurance Lake of the Ozarks Missouri: Marina Slip Liability & On-Water Protection | Dependable Brokers SEO Description: Dependable Brokers explains boat insurance Lake of the Ozarks Missouri requirements, including typical marina liability limits, pontoon, bass boat, cruiser, hull, towing, fuel-spill, and wreckage removal coverage. og:site_name: Dependable Brokers og:image:https://cdn.marblism.com/tMzmV7qbmGC.webp og:image:width: 1200 og:image:height: 630 Featured Image Alt Text: Boat insurance protection for a pontoon at a Lake of the Ozarks marina in Missouri Tags / Hashtags (30): #BoatInsurance #LakeOfTheOzarks #MissouriBoatInsurance #MarinaSlipLiability #WatercraftInsurance #PontoonInsurance #BassBoatInsurance #CruiserInsurance #OnWaterProtection #BoatLiability #BoatHullCoverage #FuelSpillCoverage #WreckageRemoval #BoatTowing #MissouriMarinas #LakeOzark #OsageBeach #Camdenton #MidMissouri #BoatingSafety #BoatTrailerInsurance #FishingBoatInsurance #MarineInsurance #PersonalWatercraft #DockLiability #BoatOwners #BoatingInMissouri #DependableBrokers #ColeCounty #BooneCounty Search Terms (12): boat insurance Lake of the Ozarks Missouri Lake Ozark marina liability insurance marina slip insurance requirements Missouri pontoon boat insurance Lake of the Ozarks bass boat insurance Missouri cruiser boat insurance Lake Ozark on-water boat insurance Missouri boat fuel spill coverage Missouri boat wreckage removal coverage boat trailer insurance Missouri marine insurance broker Mid-Missouri Randy Dinwiddie boat insurance 314-580-3455 | boat insurance lake of the ozarks missouri | Dependable Brokers Lake of the Ozarks is one of Missouri’s most active boating destinations. Whether you keep a pontoon near Osage Beach, launch a bass boat in the early morning, or spend weekends aboard a cruiser near Lake Ozark, the right policy should do more than satisfy a paperwork requirement. It should help protect your boat, your passengers, your marina relationship, and your financial goals. Missouri does not generally require boat insurance by state law. However, that does not mean you can use every marina, dock, lender, or storage facility without proof of coverage. Many slip agreements require watercraft liability insurance before your boat can be docked or stored. Some lenders also require comprehensive and collision coverage for financed vessels. What does your slip agreement require? Is the limit $300,000, $500,000, or a higher amount? Does the marina require fuel-spill protection, wreckage removal, or a certificate of insurance naming the marina as an additional interest? These details matter. Choice: Treat the marina agreement as the starting point, not the complete insurance plan. A policy can meet the minimum limit while still leaving important gaps in hull, equipment, towing, or pollution protection. 573-548-0394 | boat insurance lake of the ozarks missouri | Dependable Brokers Meet Marina Slip Liability Requirements Before Launch Day A Lake of the Ozarks boat insurance policy commonly begins with liability coverage for bodily injury and property damage. This coverage may respond when you are legally responsible for injuring another person or damaging another boat, dock, lift, seawall, or other property. Coverage requirements vary by marina, so you should confirm the exact terms directly with your slip provider. Regional insurance information commonly identifies $300,000 to $500,000 as typical liability ranges for Lake of the Ozarks marina arrangements. Larger vessels, higher speeds, frequent guest use, and significant personal assets may justify discussing higher limits or an umbrella policy. Your agent may need: The marina’s required liability limit The marina’s legal name and mailing address A certificate of insurance request Whether the marina must be listed as an additional interest The boat’s storage location and slip number The dates the boat will be in the water The vessel registration and hull identification number A certificate of insurance confirms that coverage exists, but it does not replace the policy. You still need to understand deductibles, exclusions, navigational territory, lay-up periods, and whether your personal property is included. Dependable Brokers serves Missouri customers with local knowledge and direct access to Randy Dinwiddie. Call 314-580-3455 or 573-548-0394 with your marina agreement available. When your vessel information and requirements are ready, a same-day coverage review may be possible. Advantage: Reviewing the slip requirements before docking can help you avoid delays, incomplete certificates, and last-minute policy changes. 314-580-3455 | boat insurance lake of the ozarks missouri | Dependable Brokers Protect Your Pontoon for Family Days on the Water Pontoons are popular at Lake of the Ozarks because they provide comfortable seating, stable platforms, and room for family and guests. Their liability exposure can increase when you regularly carry multiple passengers, tow inflatables, or host social outings. A pontoon policy may address: Bodily injury and property damage liability Collision with another watercraft, dock, or submerged object Comprehensive losses from theft, fire, vandalism, and severe weather Medical payments for eligible passenger injuries Personal effects, fishing equipment, and electronics Propeller and motor damage, depending on policy terms Trailer damage while transporting the pontoon On-water towing and emergency assistance Fuel-spill cleanup and wreckage removal You should also ask whether detachable equipment, furniture, canopies, ladders, and permanently installed electronics are included in the insured value. A basic liability-only policy generally will not pay to repair your own pontoon after a collision. For a newer or higher-value pontoon, ask whether the policy uses agreed value or actual cash value. Agreed value may provide a stated settlement basis for a covered total loss, while actual cash value generally considers depreciation. The exact result depends on the carrier contract. Choice: If your pontoon represents a substantial purchase, liability-only coverage may protect your marina access but not your investment. Compare the cost of physical damage coverage with the financial impact of replacing the boat yourself. 573-548-0394 | boat insurance lake of the ozarks missouri | Dependable Brokers Match Bass Boat Coverage to Speed, Gear, and Fishing Use Bass boats often have powerful outboard motors, specialized electronics, shallow-water capabilities, and expensive fishing equipment. Their insurance needs can differ from those of a family pontoon even when both boats use the same marina. When requesting a quote for bass boat insurance in Missouri, provide accurate information about: Hull make, model, year, and stated value Engine horsepower and propulsion type Trolling motor and batteries Fish finders, GPS units, and other electronics Rods, reels, tackle, and removable equipment Tournament participation or commercial use Storage location and winter lay-up plans The boat trailer and transportation frequency Why does horsepower matter? A faster vessel may create greater collision exposure and may carry a different premium than a smaller fishing boat. Why does use matter? A boat used in tournaments, transported across state lines, or operated by multiple drivers may require additional underwriting information. Your policy should also clarify whether fishing gear is covered at replacement cost or actual cash value, and whether limits apply per item or per loss. Progressive’s Missouri coverage information, for example, discusses optional protection for fishing equipment and carry-on items, while other carriers may structure those limits differently. Advantage: A detailed inventory can make your quote more accurate and help identify whether your electronics and tackle limits are practical for your actual equipment. 314-580-3455 | boat insurance lake of the ozarks missouri | Dependable Brokers Give Cruisers More Than Basic Liability Cruisers introduce additional considerations because they may include cabins, overnight accommodations, generators, air conditioning, shore-power connections, galley equipment, and larger fuel systems. A cruiser may also spend more time docked, increasing the importance of marina-related property and liability concerns. Ask about: Agreed value or actual cash value settlement Hull and machinery coverage Personal property kept inside the cabin Generator and permanently installed equipment Dockside liability Shore-power and electrical damage Salvage and wreck removal Fuel-spill or pollution liability Emergency towing and soft ungrounding Extended navigational territory Lay-up and winter storage requirements A sunken vessel can create more than a property loss. It may obstruct navigation, damage a dock, release fuel, or require specialized salvage work. BoatUS identifies towing, salvage, and spill cleanup services in the Lake of the Ozarks area, including local assistance through TowBoatUS Lake of the Ozarks. Your insurance policy and your towing membership are separate tools, so confirm what each one actually provides. If your cruiser is financed, the lender may require comprehensive and collision coverage, proof of insurance, and specific deductible limits. Send those requirements to your agent before binding coverage. Choice: Select limits based on the vessel’s value, equipment, location, and use: not only the minimum needed for a slip. 573-548-0394 | boat insurance lake of the ozarks missouri | Dependable Brokers Build a Practical Lake of the Ozarks Insurance Review Before requesting boat insurance Lake of the Ozarks Missouri, gather the information that allows an agent to move efficiently: Identify the vessel. Have the year, make, model, hull identification number, registration, purchase price, and current estimated value available. Confirm the marina rules. Ask for written liability limits, certificate instructions, additional-interest requirements, and any fuel-spill or wreckage provisions. List the equipment. Include electronics, fishing gear, removable furnishings, safety equipment, trailers, and upgraded motors. Describe how you use the boat. Explain whether you fish, tow water toys, host guests, stay overnight, participate in tournaments, or travel beyond Missouri. Review deductibles. Compare hull, comprehensive, collision, theft, and trailer deductibles. A lower premium may come with a deductible that does not fit your budget. Ask about discounts and bundling. Depending on the carrier, boating safety courses, multiple policies, responsible operation, or advance quoting may affect pricing. Plan for storage. Confirm coverage while the boat is at the marina, on a lift, in dry storage, or being transported on its trailer. Pricing is not identical from one boat owner to another. Missouri boat insurance costs can depend on vessel value, horsepower, claims history, boating experience, storage location, coverage limits, and deductible selection. One published Missouri estimate reported an average Progressive premium of $320.80 in 2024, while liability-only pricing may begin much lower. Those figures are examples, not a quote for your boat. For official boating and registration information, review the Missouri Department of Revenue watercraft resources. For local lake services, the Lake of the Ozarks Convention and Visitor Bureau marine listing provides contact information for a marine-focused agency in Lake Ozark. You can also review TowBoatUS Lake of the Ozarks for local towing, salvage, and spill-cleanup resources. Dependable Brokers brings local brokerage attention to customers throughout Mid-Missouri. Learn more about the team on the Dependable Brokers About Us page, then call Randy Dinwiddie at 314-580-3455 or 573-548-0394. Advantage: A careful review can help you satisfy the marina, protect your boat, and choose coverage that supports your broader household or business financial plan. Randy Dinwiddie Licensed agent Holts Summit Mo 65043
- Fire Damage Coverage Jefferson City MO: Insurance Protection for Your Home & Business
Focus Keyword: fire damage coverage jefferson city mo URL Slug: fire-damage-coverage-jefferson-city-mo-65101 Category: Insurance Excerpt: Learn how fire damage coverage Jefferson City MO can protect your home, belongings, temporary living expenses, commercial property, and business income after a covered fire. SEO Title: Fire Damage Coverage Jefferson City MO: Insurance Protection for Your Home & Business SEO Description: Fire damage coverage Jefferson City MO for homes and small businesses, including dwelling, smoke, contents, ALE, code upgrades, and business income. og:site_name: Dependable Brokers og:image:https://cdn.marblism.com/rfBxHJykxFU.webp og:image:width: 1200 og:image:height: 630 Featured Image Alt Text: Fire damage coverage protection for a Jefferson City Missouri home and small business in a navy and gold insurance design Tags: #FireDamageCoverageJeffersonCityMO, #JeffersonCityHomeownersInsurance, #FireInsuranceMissouri, #HomeFireInsurance, #BusinessFireInsurance, #CommercialPropertyInsurance, #SmokeDamageCoverage, #DwellingCoverage, #PersonalPropertyCoverage, #LossOfUseCoverage, #AdditionalLivingExpenses, #OrdinanceOrLawCoverage, #ReplacementCostCoverage, #ActualCashValue, #BusinessInterruptionInsurance, #BusinessIncomeCoverage, #ExtraExpenseCoverage, #FireLegalLiability, #MidMissouriInsurance, #ColeCountyInsurance, #BooneCountyInsurance, #ColumbiaMOInsurance, #HoltsSummitInsurance, #MissouriHomeownersPolicy, #CommercialInsuranceJeffersonCity, #InsuranceDeductible, #HomeInventory, #FirePrevention, #IndependentInsuranceBroker, #DependableBrokers Search Terms: fire damage coverage Jefferson City MO home fire insurance Jefferson City Missouri homeowners fire coverage commercial fire insurance Jefferson City smoke damage insurance claim Missouri replacement cost home insurance Missouri ordinance or law coverage Missouri loss of use coverage Jefferson City business interruption insurance Missouri fire insurance deductible Missouri Cole County property insurance Boone County business insurance 314-580-3455 | fire damage coverage jefferson city mo | Dependable Brokers A fire can change your household or business operations in minutes. Flames may damage the structure, while smoke, soot, water, and fire-suppression chemicals create additional losses throughout the property. If you own a home in Jefferson City, rent a commercial space near downtown, or operate a small business in Cole or Boone County, the right coverage can determine how quickly you recover. What would happen if your home required six months of repairs? What if your business could not reopen for 12 months? Would your current policy pay only the depreciated value of your belongings, or would it help you replace them? Dependable Brokers helps Mid-Missouri property owners review the coverage limits, deductibles, and endorsements that matter after a fire. You can also review the agency’s home fire insurance resource for additional information about residential protection. Advantage: A policy review before a loss gives you time to correct gaps while your options are clear. 314-580-3455 | fire damage coverage jefferson city mo | Dependable Brokers Rebuild the structure with an accurate limit For a homeowners policy, Coverage A, or dwelling coverage, is designed to repair or rebuild the primary residence after a covered fire. This may include the roof, walls, attached garage, foundation, wiring, plumbing, flooring, and permanently installed fixtures. Your dwelling limit should reflect the estimated cost to rebuild: not the property’s market value, land value, or outstanding mortgage balance. For example, if the current replacement-cost estimate for your Jefferson City home is $300,000, a $300,000 dwelling limit may be a starting point. However, construction demand, material prices, debris removal, and updated code requirements can increase the actual cost. Many policies also provide Coverage B, or other-structures coverage, for detached garages, sheds, fences, and similar property. A common default is 10% of the dwelling limit. With a $300,000 dwelling limit, that could mean $30,000 for other structures, subject to the policy terms and any applicable deductible. Some homeowners choose extended replacement cost coverage. Depending on the carrier and endorsement, the added amount may be 25% or 50% above the base dwelling limit. If a $300,000 limit has a 25% extension, the additional available amount could be $75,000, subject to the policy’s conditions. Replace belongings based on the right settlement method Coverage C, or personal property coverage, may help repair or replace furniture, clothing, electronics, appliances, tools, and other belongings damaged by fire or smoke. Your policy may settle personal property using: Actual Cash Value (ACV): The depreciated value of an item at the time of loss. Replacement Cost Value (RCV): The cost to replace an item with a similar new item, subject to policy conditions. Scheduled coverage: Additional protection for valuable jewelry, artwork, collectibles, firearms, or specialized equipment that may have standard-policy sublimits. A digital home inventory with photographs, receipts, model numbers, and serial numbers can make documentation easier. Store a copy in secure cloud storage so it remains available if the home is inaccessible. Choice: Lower limits and ACV settlement may reduce premiums, but higher limits and replacement-cost options can better protect your long-term financial position after a total loss. 314-580-3455 | fire damage coverage jefferson city mo | Dependable Brokers Pay for temporary housing while your home is restored A major fire can make your residence uninhabitable even when part of the structure remains standing. Coverage D, commonly called Loss of Use or Additional Living Expense coverage, may pay the necessary increase in living costs after a covered loss. Depending on the policy, covered expenses may include: Temporary rental housing or extended-stay lodging Additional meal costs when you cannot use your kitchen Storage for salvageable furniture and personal property Transportation changes caused by temporary relocation Pet boarding when required by the covered loss Many homeowners policies use a Loss of Use limit equal to approximately 20% to 30% of the dwelling limit. If your dwelling is insured for $300,000, that range could be $60,000 to $90,000. The actual limit, duration, and covered expenses depend on your policy. Is your temporary-housing limit realistic for Jefferson City rental prices and rebuilding delays? A short repair can become a long project when there is structural damage, smoke remediation, permitting, or contractor scarcity. Treat smoke and water damage as part of the recovery plan Smoke and soot can spread through HVAC systems, insulation, carpet, clothing, and furniture. Even rooms untouched by flames may require professional cleaning, deodorizing, duct treatment, or replacement of porous materials. Water damage from firefighting efforts may also occur during a covered fire loss. The policy determines how resulting water damage is handled, so you should report all related damage promptly rather than assuming only visibly burned areas matter. Missouri’s Department of Commerce and Insurance advises consumers to document damage, take photographs before making temporary repairs when safe, keep receipts, and contact the insurer promptly. You can review the department’s insurance consumer guidance for claim-preparation information. Advantage: Strong Loss of Use coverage helps you maintain stability while professionals address smoke, water, structural, and contents damage. 314-580-3455 | fire damage coverage jefferson city mo | Dependable Brokers Protect the building, inventory, and equipment For a small business, fire damage can affect more than the building. A commercial property policy or Business Owners Policy may protect: The commercial building, if you own it Tenant improvements and betterments Inventory, supplies, furniture, and fixtures Computers, point-of-sale equipment, machinery, and tools Outdoor signs, fencing, and other insured property Debris removal and selected cleanup expenses A $500,000 commercial property limit may sound substantial, but is it enough to rebuild the structure, replace equipment, restore inventory, and meet current building requirements? Commercial limits should be based on updated replacement-cost estimates and realistic inventory values. If you lease a storefront or office, your landlord’s policy generally protects the building owner’s interest: not necessarily your inventory, equipment, improvements, or liability exposure. Fire legal liability may help address your responsibility for fire damage to rented premises, subject to the policy limit and exclusions. Keep revenue moving with business income coverage Physical property coverage does not automatically replace all revenue lost during a shutdown. Business income coverage, also called business interruption insurance, may help replace lost net income and continuing operating expenses after a covered fire causes direct physical damage. Important policy details include: The business income dollar limit The period of restoration A waiting period, often 48 to 72 hours Payroll and continuing expense treatment Extra Expense coverage for temporary space, equipment, or expedited operations Civil authority or dependent-property provisions, when available For example, a business with $40,000 in monthly continuing expenses could face $480,000 in costs over 12 months before considering lost profit. Your limit and restoration period should reflect your actual financial statements, seasonality, lease obligations, payroll, and likely rebuilding timeline. Dependable Brokers provides a business insurance consultation for owners who want to review commercial fire insurance, liability, and business continuity needs. Choice: Property coverage protects what your business owns; business income and Extra Expense coverage help protect how your business earns. 314-580-3455 | fire damage coverage jefferson city mo | Dependable Brokers Match your policy to Mid-Missouri conditions Insurance pricing and underwriting can vary by location, construction, occupancy, fire-protection class, roof age, electrical systems, distance from fire services, and prior claims. A property in Jefferson City may have different underwriting characteristics than a rural home outside city limits or a business location in Columbia. Review these items annually: Replacement cost: Confirm Coverage A or commercial building limits reflect current construction prices. Deductible: A $1,000 or $2,500 all-perils deductible is common in many policies, but verify your declarations page. Ordinance or Law: This coverage may help pay increased costs required by current building codes after a covered fire. Contents limits: Confirm furniture, tools, electronics, inventory, and specialty property are adequately insured. Loss of Use or Business Income: Check dollar limits, waiting periods, and restoration periods. Exclusions: Standard homeowners policies generally cover fire and lightning, but flood and earthquake damage commonly require separate coverage. Liability: Review personal liability or commercial general liability limits if a fire causes damage to another person’s property. Missouri does not generally require homeowners insurance by state law, but mortgage lenders commonly require it as a condition of financing. Commercial leases, lenders, and contracts may also require specific property and liability limits. Advantage: Local review helps connect policy language to the actual home, business, building codes, and financial obligations you face in Jefferson City, Columbia, Cole County, and Boone County. 314-580-3455 | fire damage coverage jefferson city mo | Dependable Brokers Request a prompt coverage review You do not have to wait until smoke is visible to review your protection. Gather your declarations page, recent renovations, home inventory, commercial property values, equipment list, lease information, and current revenue figures. Then call 314-580-3455 and ask for Randy Dinwiddie. A prompt review can identify whether your limits, deductible, replacement-cost terms, ordinance-or-law coverage, Loss of Use, business income, and fire legal liability protection still fit your needs. Dependable Brokers serves families and small business owners throughout Jefferson City, Columbia, Holts Summit, Cole County, and Boone County. The goal is straightforward: help you understand what you are buying, what it may pay, and where additional protection may be appropriate. Coverage terms vary by carrier, policy form, endorsements, exclusions, limits, and deductibles. This article is general educational information and is not a substitute for reviewing your policy with a licensed insurance professional. Randy Dinwiddie Licensed agent Holts Summit Mo 65043 Visit Dependable Brokers or call 314-580-3455 for your fire damage coverage Jefferson City MO review. Sources:Missouri Department of Commerce and Insurance severe-weather insurance guidance · Missouri Department of Commerce and Insurance flood coverage information · Dependable Brokers home fire insurance information · Dependable Brokers commercial fire insurance information
- Farm Truck Insurance Jefferson City MO: Specialized Agricultural Vehicle Coverage
SEO Back-End Focus Keyword: farm truck insurance jefferson city mo URL Slug: farm-truck-insurance-jefferson-city-mo-65101 Category: Dependable Brokers (Insurance) Excerpt: Learn how farm truck insurance in Jefferson City, MO can address agricultural vehicles, hauling liability, cargo exposure, physical damage, and practical risk management for Cole County farm operations. SEO Title: Farm Truck Insurance Jefferson City MO: Specialized Agricultural Vehicle CoverageAmerishop Services LLC SEO Advertisinghttps://cdn.marblism.com/wgrrLYbC8ZC.webp SEO Description: Amerishop Services LLC SEO Advertising Farm truck insurance in Jefferson City, MO for agricultural vehicles, Cole County hauling liability, cargo, trailers, and practical risk management.https://cdn.marblism.com/wgrrLYbC8ZC.webp og:site_name: Amerishop Services LLC SEO Advertising og:image:https://cdn.marblism.com/wgrrLYbC8ZC.webp og:image:width: 1200 og:image:height: 630 Featured Image Alt Text: Farm truck insurance in Jefferson City Missouri with agricultural vehicles, farm fields, and protective coverage imagery Tags / Hashtags (30): #FarmTruckInsurance #FarmInsurance #AgriculturalVehicleInsurance #JeffersonCityMO #ColeCountyMO #MissouriFarmInsurance #FarmAutoInsurance #CommercialAutoInsurance #HaulingLiability #MotorTruckCargo #FarmTruckCoverage #AgriculturalBusiness #MissouriAgriculture #FarmRiskManagement #RuralInsurance #TruckLiability #TrailerInsurance #GrainHauling #LivestockHauling #FarmEquipmentInsurance #UninsuredMotoristCoverage #PhysicalDamageCoverage #GeneralLiabilityInsurance #CommercialInsurance #SmallBusinessInsurance #MidMissouriInsurance #HoltsSummitMO #BooneCountyMO #FarmSafety #DependableBrokers Search Terms (12): farm truck insurance Jefferson City MO, agricultural vehicle insurance Cole County, Missouri farm auto insurance, farm truck liability coverage, farm cargo insurance Missouri, grain hauling insurance Jefferson City, livestock hauling liability Missouri, farm trailer insurance Cole County, commercial truck insurance Jefferson City, farm equipment insurance Mid-Missouri, agricultural business insurance Missouri, farm risk management Jefferson City 314-580-3455 | farm truck insurance jefferson city mo | Dependable Brokers If you operate a farm in Jefferson City, Cole County, or the surrounding Mid-Missouri area, your truck may do much more than carry tools. It may transport hay, grain, livestock, fertilizer, feed, equipment, or harvested products between fields, storage sites, markets, and processing locations. That use creates a different insurance profile from ordinary personal driving. A farm pickup used occasionally on private property may need a different policy structure than a grain truck traveling on Missouri highways. A truck hauling your own products may also be treated differently from a vehicle hauling goods for another person or business for compensation. So what should you review before renewing your policy or adding an agricultural vehicle? The starting point is a clear description of how you use the truck, where it travels, what it carries, who drives it, and whether you are hauling only your own farm products or operating as a carrier. Dependable Brokers can help you organize those details and discuss coverage options with Randy Dinwiddie at 314-580-3455 or 573-548-0394. Choice summary: The right policy begins with accurate use information: not simply the year, make, and model of the truck. 314-580-3455 | farm truck insurance jefferson city mo | Dependable Brokers Protect the vehicle that keeps your operation moving. Farm truck insurance may address several separate exposures. Your final policy depends on underwriting, vehicle classification, registration, usage, limits, deductibles, exclusions, and carrier forms. However, a practical review commonly includes: Auto liability: Coverage for qualifying bodily injury and property damage claims when you are legally responsible. Uninsured and underinsured motorist coverage: Protection for covered bodily injury involving a driver who has no insurance or insufficient limits, subject to the policy. Collision coverage: Protection for covered damage caused by a collision or upset. Other-than-collision coverage: Often called comprehensive coverage, this may address covered losses such as theft, fire, falling objects, or vandalism. Trailer coverage: A stock trailer, utility trailer, grain trailer, or equipment trailer may need to be specifically listed or addressed by the policy. Emergency road service: Useful when a loaded truck breaks down away from the farm. Motor truck cargo coverage: Important when your operation has legal responsibility for transported goods under a hauling arrangement. General liability or farm liability: May address premises and operational exposures that do not belong under the vehicle policy. Umbrella liability: Additional liability limits may be appropriate for larger operations, multiple vehicles, hired drivers, or substantial farm assets. The Missouri Farm Bureau commercial auto program identifies farm trucks, utility and stock trailers, grain trucks, semi-trucks and trailers, dump trucks, and other commercial vehicles as categories that may require specialized coverage. Its listed options include liability, collision, comprehensive, uninsured motorists, underinsured motorists, emergency road service, and motor truck cargo, subject to policy terms. You can review the Missouri Farm Bureau commercial auto coverage overview as a general reference. For broader farm vehicle concepts, the Farm Bureau Financial Services farm vehicle page explains why trucks, trailers, tractors, and other agricultural vehicles should be evaluated according to their actual use. Advantage summary: A scheduled, accurately described vehicle policy can help reduce uncertainty when your truck is used for both farm work and highway travel. 314-580-3455 | farm truck insurance jefferson city mo | Dependable Brokers Match liability limits to the size of the risk. Missouri’s Department of Revenue identifies minimum motor vehicle financial responsibility limits of: $25,000 for bodily injury to one person $50,000 for bodily injury to two or more people in one accident $25,000 for property damage in one accident $25,000 per person and $50,000 per accident for uninsured motorist bodily injury coverage You can verify current state information through the Missouri Department of Revenue insurance information page. These limits may satisfy a baseline legal requirement, but are minimums: not a recommendation for every farm operation. Consider the potential value of your truck, trailer, cargo, equipment, land improvements, savings, and business income. If a loaded truck is involved in a serious crash near Jefferson City, would minimum limits be enough to protect your financial goals? Your answer may depend on: Whether you regularly use public highways The number and type of vehicles you operate Whether you haul livestock or valuable equipment Whether employees or seasonal workers drive Whether customers, neighbors, or contractors rely on your hauling Whether you travel outside Cole County Whether you operate across state lines Whether a lender requires specified physical damage coverage Whether contracts require certificates of insurance or higher limits For-hire or interstate hauling can create additional compliance issues. Commercial truck programs may involve filings such as Form E, MCS-90, Form H, ICC filings, or other requirements depending on the operation. Progressive Commercial’s Missouri commercial truck insurance resource describes several filing categories and distinguishes owner-operator, private carrier, and motor carrier situations. Do not assume that a farm-use designation automatically answers every insurance question. Tell your agent exactly what you do. Choice summary: Minimum limits address the legal baseline; appropriate limits address the financial consequences of your actual operation. 314-580-3455 | farm truck insurance jefferson city mo | Dependable Brokers Close the gaps created by hauling and cargo. Hauling liability deserves special attention for Cole County farms. Your exposure may change depending on whether you transport: Your own hay, grain, livestock, or equipment Products owned by a neighboring farm Cargo for a cooperative or processor Materials for compensation Fertilizer, chemicals, or other potentially hazardous products Equipment belonging to a customer or contractor A farm truck policy may not automatically provide the same protection as a commercial motor truck policy. Cargo coverage can also be limited by the type of goods, the cause of loss, the transportation agreement, the valuation method, and exclusions for wear, deterioration, improper loading, or ordinary handling. Before accepting a hauling job, ask: Who owns the cargo? Who is legally responsible while it is in transit? Is there a written contract, bill of lading, or shipping receipt? What is the maximum value of one load? Does the trailer belong to you or another party? Does the route remain in Missouri? Are special permits, registrations, or filings required? Does the customer require a certificate of insurance? A written load-securement procedure can be as important as the insurance review. Keep cargo within weight limits, inspect tie-downs, check trailer lights and tires, and document pre-trip inspections. Maintain driver records and confirm that every regular driver is disclosed to the insurer. Advantage summary: Clear ownership, contract, cargo, and route information helps your agent identify whether farm auto, commercial auto, motor truck cargo, or additional liability coverage may be appropriate. 314-580-3455 | farm truck insurance jefferson city mo | Dependable Brokers Use a local risk review to improve practical protection. Jefferson City and Cole County operations face familiar rural risks: narrow roads, changing weather, soft shoulders, farm entrances, livestock movement, seasonal traffic, and long distances between fields and storage locations. Your risk-management plan should reflect the way your operation actually functions. Before requesting a quote, gather: Year, make, model, VIN, and current value for each truck Gross vehicle weight rating and registered weight Farm plate or commercial registration information Trailer type, value, and ownership Typical cargo and maximum load value Annual mileage and operating radius Driver names, ages, licenses, and driving histories Claims history and current declarations pages Lender or contract insurance requirements Details about hired, seasonal, or family drivers Then review your operation at least annually and whenever you add a vehicle, change the type of hauling, hire a driver, begin serving customers, or expand beyond Missouri. Dependable Brokers serves Mid-Missouri families, vehicle owners, and small businesses with local insurance guidance. You can also review the Dependable Brokers business insurance consultation page for information about scheduling a conversation with Randy Dinwiddie. For background on the agency and contact information, visit the Dependable Brokers About Us page. For a prompt review of your farm truck insurance needs, call Randy Dinwiddie at 314-580-3455 or 573-548-0394. Bring your vehicle list, hauling details, and current policy documents so the conversation can move efficiently. Choice summary: Practical local information gives you a stronger foundation for comparing coverage, limits, deductibles, and costs honestly. 314-580-3455 | farm truck insurance jefferson city mo | Dependable Brokers Farm truck insurance in Jefferson City, MO should be built around your operation: not a generic assumption about how a pickup is used. Agricultural vehicles, trailers, cargo, employees, seasonal drivers, and hauling arrangements can each change the coverage conversation. Review Missouri’s 25/50/25 financial responsibility baseline, then consider whether your assets and hauling activities call for higher limits or additional protection. Confirm how your policy addresses physical damage, uninsured motorists, trailers, cargo, farm premises liability, and commercial use. The right next step is a direct policy review with a licensed professional who can evaluate your specific farm operation in Jefferson City or Cole County. Randy Dinwiddie Licensed agent Holts Summit Mo 65043
- Work Truck Insurance Mid Missouri: Robust Coverage for Contractors and Fleets
━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━ Focus Keyword: work truck insurance mid missouri URL Slug: work-truck-insurance-mid-missouri-65101 Category: Dependable Brokers (Insurance) Excerpt: Work truck insurance Mid Missouri can combine commercial auto protection, contractor tools coverage, fleet options, and general liability guidance for contractors in Jefferson City, Columbia, Cole County, and Boone County. SEO Title: Work Truck Insurance Mid Missouri: Robust Coverage for Contractors and Fleets SEO Description: Work truck insurance Mid Missouri for contractors and fleets with commercial auto, tools and equipment, general liability guidance, and local brokerage support. og:site_name: Dependable Brokers og:image:https://cdn.marblism.com/dMsW2tDarKv.webp og:image:width: 1200 og:image:height: 630 Featured Image Alt Text: Work truck insurance Mid Missouri protection for contractors and commercial fleets near a Missouri job site Tags: work truck insurance mid missouri, commercial auto insurance Missouri, contractor insurance Missouri, contractor tools coverage, inland marine insurance Missouri, work truck insurance Jefferson City, work truck insurance Columbia MO, commercial truck insurance Cole County, commercial auto Boone County, small business insurance Mid Missouri, fleet insurance Missouri, F-150 work truck insurance, pickup truck insurance for contractors, general liability insurance Missouri, business auto insurance, contractor equipment insurance, jobsite insurance, hired and non-owned auto, uninsured motorist coverage Missouri, 25/50/25 Missouri insurance, one million CSL commercial auto, Mid Missouri insurance broker, Dependable Brokers, DealMaker Motors listings, contractor fleet protection, construction insurance Missouri, landscaping insurance Missouri, HVAC contractor insurance, electrical contractor insurance, plumbing contractor insurance Search Terms: work truck insurance mid missouri commercial auto insurance Jefferson City MO contractor truck insurance Columbia Missouri F-150 commercial insurance Mid Missouri contractor tools insurance Missouri inland marine insurance for contractors fleet insurance Cole County commercial auto insurance Boone County business insurance for contractors Missouri work vehicle insurance near Holts Summit general liability and commercial auto package insurance for construction work trucks Hashtags: #WorkTruckInsurance #MidMissouriInsurance #CommercialAuto #ContractorInsurance #ContractorTools #InlandMarine #FleetInsurance #MissouriBusiness #JeffersonCityMO #ColumbiaMO #ColeCounty #BooneCounty #F150WorkTruck #WorkTruckCoverage #BusinessAuto #GeneralLiability #ConstructionInsurance #LandscapingInsurance #HVACInsurance #ElectricalContractor #PlumbingContractor #JobsiteProtection #HiredNonOwnedAuto #UninsuredMotorist #CommercialFleet #SmallBusinessInsurance #InsuranceBroker #DependableBrokers #DealMakerMotors #MissouriContractors 314-580-3455 | work truck insurance mid missouri | Dependable Brokers If your pickup is part of how you earn a living, it needs protection designed around business use: not assumptions made for a personal vehicle. Work truck insurance Mid Missouri helps contractors, tradespeople, and small fleets protect the vehicle, the business, and the equipment that keeps every job moving. Whether you operate in Jefferson City, Columbia, Holts Summit, Cole County, or Boone County, your risk profile may include job-site travel, material hauling, employee drivers, trailers, tools, and customer property. A Ford F-150 work truck can be an efficient foundation for a growing business, but the right insurance should be reviewed before you put it into daily service. Dependable Brokers can help you coordinate coverage while you review available DealMaker Motors vehicle listings. Ask what the truck will carry, who will drive it, where it will travel, and whether it will be titled personally or to your business. Those details can affect eligibility, limits, deductibles, and premium. Choice: Buy or place a work truck into service with a clear coverage plan instead of discovering a business-use limitation after a loss. 314-580-3455 | work truck insurance mid missouri | Dependable Brokers 314-580-3455 | work truck insurance mid missouri | Dependable Brokers Start With Missouri’s Financial Responsibility Rules Missouri law requires owners of registered motor vehicles to maintain financial responsibility before operating those vehicles. Missouri Revised Statutes §303.025 explains the duty to maintain financial responsibility and the possible consequences of operating without it. For many Missouri drivers, the familiar liability benchmark is: $25,000 for bodily injury to one person $50,000 for bodily injury to two or more people in one accident $25,000 for property damage in one accident That is commonly called 25/50/25 coverage. Uninsured motorist protection is also an important part of the Missouri insurance discussion. You can review Missouri motor vehicle insurance resources through the Missouri Department of Revenue. But is the state minimum enough for your contracting business? A minimum limit may satisfy a legal requirement while leaving your business exposed to a serious claim, damaged equipment, lost work time, or a contract requirement you cannot meet. Many commercial agreements and municipal projects request a $1,000,000 combined single limit, often called $1M CSL, even when the state minimum is lower. Your broker should compare the legal baseline with the practical requirements of your work. Advantage: Legal compliance is the starting point. Contract-ready limits and business-specific coverage help create a more resilient protection plan. 573-548-0394 | work truck insurance mid missouri | Dependable Brokers 573-548-0394 | work truck insurance mid missouri | Dependable Brokers Match Commercial Auto Coverage to the Work You Actually Do A personal auto policy may not be designed for regular business use, transporting tools, hauling supplies, visiting job sites, or allowing employees to operate the vehicle. Commercial auto insurance is structured around those business exposures. A work truck insurance review may include: Commercial auto liability: Helps address bodily injury and property damage claims you cause while operating the truck for business. Collision coverage: Helps repair or replace the insured vehicle after a covered collision, subject to the policy deductible and terms. Comprehensive coverage: May respond to covered losses such as theft, vandalism, hail, falling objects, or certain weather-related damage. Uninsured and underinsured motorist coverage: Helps protect you and covered occupants when another driver has no insurance or insufficient limits, subject to policy terms. Medical payments coverage: May help with covered medical expenses for occupants after an accident. Hired and non-owned auto: Useful when your business rents a vehicle or employees use personally owned vehicles for company errands. Trailer coverage: Important when you use an enclosed trailer, utility trailer, or equipment trailer as part of your operation. Additional insured and certificate support: Frequently requested by general contractors, property managers, municipalities, or commercial customers. The right policy depends on whether you are a solo electrician, a landscaping company with several crews, an HVAC contractor, a plumber, a remodeler, or a construction company hauling materials. Vehicle weight, radius of operation, driver history, ownership, garaging location, and annual mileage can all affect underwriting. Choice: Select limits and endorsements based on your actual route, equipment, contracts, and drivers: not simply on the truck’s purchase price. 314-580-3455 | work truck insurance mid missouri | Dependable Brokers 314-580-3455 | work truck insurance mid missouri | Dependable Brokers Protect the Tools Inside and Around the Truck A commercial auto policy protects the vehicle and covered vehicle-related exposures. It may not fully protect every portable tool, material, or piece of equipment you carry from one job to another. That is where contractor tools coverage, often called inland marine insurance or contractors equipment insurance, may help. The tools and equipment coverage overview from Progressive Commercial describes protection for movable tools and equipment that travel to job sites, remain in vehicles, or are stored away from the primary business location. Your equipment list may include: Cordless drills and saws Nail guns and compressors Ladders and generators Welding equipment Specialty plumbing or electrical tools Lawn mowers, trimmers, and chainsaws Materials waiting for installation Portable computers, testing devices, and job-site electronics Keep receipts, serial numbers, photographs, and replacement-cost estimates for higher-value items. Ask whether coverage applies in the truck overnight, at an active job site, during transit, and in temporary storage. Also ask about deductibles, per-item limits, scheduled equipment, rented equipment, and exclusions for wear and tear or unattended property. Permanently attached items: such as a mounted vacuum system, built-in toolbox, or specialized truck equipment: may need to be evaluated under commercial auto rather than portable tools coverage. Advantage: Separating vehicle protection from movable equipment protection can reduce the chance that an expensive tool loss falls into an unexpected coverage gap. 573-548-0394 | work truck insurance mid missouri | Dependable Brokers 573-548-0394 | work truck insurance mid missouri | Dependable Brokers Build a Fleet Plan Before One Truck Becomes Three Many Mid-Missouri businesses begin with one pickup and later add a second truck, a service van, or a trailer. A fleet review can help you keep driver assignments, vehicle schedules, garaging locations, and coverage limits organized as the business grows. A small fleet discussion should address: Who drives each vehicle? Are drivers employees, owners, or occasional helpers? Are any drivers under age 25? Does the business run only in Cole County and Boone County, or throughout Missouri? Are trucks used for deliveries, hauling, service calls, or transporting customers? Are trailers and permanently installed equipment listed correctly? Do customers require certificates of insurance or $1M CSL? Are vehicles financed, leased, or owned outright? Fleet pricing is not automatically cheaper in every situation, but consistent underwriting and accurate schedules may make administration easier. A complete review can also identify whether general liability, workers’ compensation, umbrella coverage, or hired and non-owned auto should be considered alongside commercial auto. If you are purchasing an F-150 through a DealMaker Motors listing, get the vehicle details to your insurance professional before finalizing the transaction. Year, trim, use, value, modifications, ownership, and financing information can all matter. Choice: Grow with a coordinated commercial insurance plan instead of adding vehicles one at a time without checking how the changes affect your overall risk. 314-580-3455 | work truck insurance mid missouri | Dependable Brokers 314-580-3455 | work truck insurance mid missouri | Dependable Brokers Get a Clear Quote Without the Guesswork Honest pricing begins with accurate information. Commercial auto premiums can vary based on driving records, claims history, vehicle type, radius, annual mileage, business classification, limits, deductibles, and the value of attached or transported equipment. No responsible broker should promise one universal price for every Mid-Missouri contractor. Dependable Brokers can help you organize the information carriers typically need: Business legal name and ownership structure Vehicle identification number and purchase documents Driver names and motor vehicle records Business address and overnight garaging location Description of contracting operations Estimated annual mileage and travel radius Tool and equipment inventory Current insurance declarations pages Contractual insurance requirements Loss history and prior coverage information The Dependable Brokers business insurance consultation currently lists a one-hour consultation at $199. Confirm the current fee and appointment availability before booking. That transparent consultation option can be useful when your application involves several vehicles, contractor tools, general liability, or project-specific requirements. For a quick initial review, contact Randy Dinwiddie at 314-580-3455 or Rachel at 573-548-0394. Have your vehicle information and current declarations page available so the conversation can move efficiently. Advantage: A prepared application supports faster comparison, fewer follow-up questions, and a more accurate discussion of coverage and cost. 314-580-3455 | work truck insurance mid missouri | Dependable Brokers 314-580-3455 | work truck insurance mid missouri | Dependable Brokers Your Mid-Missouri Coverage Checklist Before driving your next work truck to a job site, confirm that you have reviewed: Commercial auto liability limits Missouri financial responsibility requirements Uninsured motorist coverage Collision and comprehensive deductibles Trailer and permanently attached equipment Contractor tools or inland marine coverage Hired and non-owned auto exposure General liability requirements Employee and subcontractor arrangements Contractual certificate requirements Vehicle ownership and lender requirements Fleet changes and driver assignments Work truck insurance Mid Missouri should support your financial goals, your customers, and your ability to keep operating after an unexpected event. Whether you are protecting one F-150 in Jefferson City or coordinating a growing fleet across Columbia, Cole County, and Boone County, a local review can help you make an informed decision without unnecessary complexity. Start with the truck, then review the tools, drivers, contracts, and business operations connected to it. Call 314-580-3455 or 573-548-0394 for a practical coverage conversation with Dependable Brokers. Choice: Protect the asset that gets you to the job: and the business that depends on getting there. Randy Dinwiddie Licensed agent Holts Summit Mo 65043 CONTINUE HOME ━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
- Commercial Auto Insurance Jefferson City MO: Fleet & Business Vehicle Protection
Focus Keyword: commercial auto insurance jefferson city mo URL Slug: commercial-auto-insurance-jefferson-city-mo-65101 Category: Dependable Brokers (Insurance) Excerpt: Commercial auto insurance Jefferson City MO coverage for business vehicles, fleets, cargo, hired and non-owned autos, and general liability coordination with transparent pricing and local support. SEO Title: Commercial Auto Insurance Jefferson City MO: Fleet & Business Vehicle Protectionhttps://cdn.marblism.com/UbowBGA3tVT.webp SEO Description: Commercial auto insurance Jefferson City MO coverage for fleets, cargo, business vehicles, and general liability coordination with transparent pricing.https://cdn.marblism.com/UbowBGA3tVT.webp og:site_name: Dependable Brokers og:image:https://cdn.marblism.com/UbowBGA3tVT.webp og:image:width: 1200 og:image:height: 630 Featured Image Alt Text: Commercial auto insurance Jefferson City MO protection for business fleets, cargo, and work vehicles Tags (30): #CommercialAutoInsurance, #JeffersonCityMO, #FleetInsurance, #BusinessVehicleInsurance, #MissouriInsurance, #CargoInsurance, #GeneralLiability, #CommercialTruckInsurance, #CommercialVanInsurance, #SmallBusinessInsurance, #ColeCountyBusiness, #BooneCountyBusiness, #MidMissouriBusiness, #HoltsSummitMO, #BusinessAutoCoverage, #WorkTruckInsurance, #DeliveryVehicleInsurance, #ContractorInsurance, #TransparentPricing, #DealerFreeInsurance, #AutoLiability, #UninsuredMotoristCoverage, #CollisionCoverage, #ComprehensiveCoverage, #HiredNonOwnedAuto, #RandyDinwiddie, #DependableBrokers, #JeffersonCityBusiness, #FleetRiskManagement, #MissouriSmallBusiness Search Terms (12): commercial auto insurance Jefferson City MO fleet insurance Jefferson City Missouri business vehicle insurance Cole County commercial truck insurance Holts Summit MO cargo insurance for Missouri businesses general liability and commercial auto insurance delivery van insurance Jefferson City contractor vehicle insurance Mid-Missouri transparent commercial insurance pricing hired and non-owned auto insurance Missouri work truck insurance near Jefferson City Randy Dinwiddie commercial insurance agent ━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━ 314-580-3455 | commercial auto insurance jefferson city mo | Dependable Brokers Your business vehicles are more than transportation. They carry tools, inventory, employees, equipment, and the earning power of your company. If a work van is damaged, a driver causes an accident, or cargo is stolen in transit, the financial impact can extend far beyond the repair bill. That is why commercial auto insurance Jefferson City MO businesses can rely on should be designed around how you actually operate. A single service pickup, a group of delivery vans, a contractor fleet, or a combination of trucks and trailers each creates a different risk profile. Dependable Brokers serves business owners in Jefferson City, Holts Summit, Columbia, Cole County, Boone County, and surrounding Mid-Missouri communities. Through the Dependable Brokers business insurance consultation, you can review vehicle use, driver information, cargo, liability limits, and policy structure with a local licensed agent. Why does this matter? A personal auto policy may not be designed for regular commercial use, employee drivers, deliveries, tools, customer property, or business-owned vehicles. Correct classification at the beginning can help prevent coverage questions after a loss. Advantage: You receive a policy discussion based on your business activity rather than a generic personal auto quote. 314-580-3455 | commercial auto insurance jefferson city mo | Dependable Brokers Build coverage around your entire fleet Commercial auto liability is the foundation of a business vehicle policy. In Missouri, commonly cited minimum auto liability limits are: $25,000 bodily injury per person $50,000 bodily injury per accident $25,000 property damage per accident These limits are commonly described as 25/50/25. Uninsured and underinsured motorist requirements and available options should be confirmed for your specific policy and vehicle use. If your company has contracts, financed vehicles, larger trucks, passenger transportation, or interstate operations, the minimum limits may not satisfy your lender, customer, lease, or regulatory obligations. Many commercial contracts request substantially higher limits. Some may request a $1 million combined single limit, but that amount is not automatically appropriate for every business. The right limit depends on your operations, assets, contracts, vehicle types, driving radius, and cargo exposure. A commercial auto review may include: Owned business autos Leased or financed vehicles Employee vehicles used for company errands Hired autos rented for business purposes Non-owned autos used by employees Service pickups and contractor trucks Delivery vans and passenger vehicles Utility, equipment, and commercial trailers Heavy-duty trucks and specialty vehicles Physical damage coverage is also important when your vehicle is a productive business asset. Collision coverage generally addresses damage from a crash, while comprehensive coverage, also called other-than-collision coverage, may address theft, fire, hail, vandalism, animal strikes, and other covered losses. Deductibles directly affect your out-of-pocket cost and should be selected with your cash flow in mind. Choice: Choose limits and deductibles based on the cost of replacing a vehicle, protecting business assets, and meeting contract requirements: not only the lowest initial premium. 314-580-3455 | commercial auto insurance jefferson city mo | Dependable Brokers Protect the cargo inside the vehicle Your truck or van may be insured while the property inside it is not automatically covered in the same way. Cargo exposure should be reviewed separately, especially if you transport building materials, appliances, tools, inventory, food, electronics, or customer property. Motor truck cargo coverage may be available as part of a commercial insurance program or through an endorsement or companion policy. Coverage terms can vary based on: Type of goods transported Maximum value of one shipment Average value carried each day Theft and unattended vehicle exposure Refrigerated or temperature-sensitive goods Loading and unloading responsibilities Delivery territory and driving radius Contractual requirements from customers Exclusions for certain materials or operations For example, if your largest routine shipment is valued at $75,000, you should ask whether your cargo limit, deductible, and exclusions are appropriate for that exposure. Do not assume the vehicle’s physical damage limit automatically protects customer property or inventory inside the vehicle. Missouri Farm Bureau’s commercial auto coverage overview identifies motor truck cargo among available commercial coverage features, along with liability, medical payments, uninsured motorists, collision, comprehensive, emergency road service, and employers non-owner liability. Actual protection depends on the policy form, endorsements, exclusions, and conditions. Advantage: A coordinated review helps connect the vehicle, the cargo, and the business operation instead of treating each exposure as an isolated purchase. 314-580-3455 | commercial auto insurance jefferson city mo | Dependable Brokers Coordinate commercial auto with general liability Commercial auto insurance and general liability insurance serve different purposes. Commercial auto generally addresses liability arising from the use of covered vehicles. General liability typically addresses third-party bodily injury, property damage, and advertising injury connected to premises and business operations. Consider these examples: Your employee rear-ends another vehicle while making a delivery: commercial auto may respond. A customer slips inside your office: general liability may respond. Your technician damages a customer’s property while performing work: general liability may respond, subject to the policy. A company vehicle hits a parked car at a job site: commercial auto may respond. An employee uses a personal vehicle for a company errand: hired and non-owned auto coverage should be reviewed. A general liability policy does not automatically replace commercial auto coverage. Likewise, commercial auto does not replace general liability for premises, completed operations, or many non-auto business risks. Contractors, delivery companies, service businesses, restaurants, retailers, and property managers often need both policies coordinated. You may also need to review workers’ compensation, commercial property, tools and equipment, umbrella liability, professional liability, or pollution coverage depending on your work. The goal is not to purchase every available endorsement. The goal is to identify where one policy ends and another begins. Choice: Ask for a coverage map showing which policy responds to vehicle accidents, cargo losses, customer injuries, employee drivers, and operational claims. 314-580-3455 | commercial auto insurance jefferson city mo | Dependable Brokers See the price before you commit Commercial insurance pricing is not a universal monthly number. Premiums can change based on: Number of vehicles Vehicle make, model, age, weight, and value Driver age, experience, violations, and claims history Business type and vehicle use Local, statewide, or interstate driving radius Cargo type and maximum value Liability limits Collision and comprehensive deductibles Vehicle garaging location Prior insurance and loss history Payment plan and selected endorsements Transparent pricing means your proposal should identify the premium and explain the cost of selected coverages, deductibles, endorsements, down payment, installment charges, and applicable carrier fees. Ask directly: What is included, what is optional, and what amount is due today? Dependable Brokers’ dealer-free approach is focused on clear coverage discussions without hidden dealer-style add-ons. That does not mean every policy has the same price or that insurance has no taxes, carrier charges, or underwriting conditions. It means you should be able to understand what you are paying for before binding coverage. For a faster review, prepare your vehicle schedule, VINs, driver roster, current declarations page, loss history, cargo description, estimated mileage, operating radius, and contract requirements. Randy Dinwiddie and Rachel can begin the intake process at 314-580-3455 or 573-548-0394. When the application information is complete, ask about a targeted 24-hour quote review; final timing remains subject to carrier underwriting and document verification. Advantage: Clear information produces a more useful comparison than a headline premium with unknown exclusions or fees. 314-580-3455 | commercial auto insurance jefferson city mo | Dependable Brokers Your next step in Jefferson City Whether you operate one work vehicle in Holts Summit or a larger fleet serving Jefferson City, Columbia, and surrounding Mid-Missouri communities, your insurance should keep pace with the work your vehicles perform. Before renewal or before adding another truck, ask: Are all business-owned and regularly used vehicles classified correctly? Do our liability limits satisfy customer and lender requirements? Is cargo covered at its maximum routine value? Do we need hired and non-owned auto coverage? Are deductibles appropriate for our cash reserves? Does our general liability policy coordinate with commercial auto? Can we see every premium component and optional charge? You can also review the existing commercial auto insurance information from Dependable Brokers before scheduling a conversation. Policy forms control coverage, so ask for the actual terms, exclusions, and endorsements applicable to your quote. Choice: Protect the vehicles that generate your revenue, the cargo your customers trust you to carry, and the business assets behind every trip. Call Randy Dinwiddie at 314-580-3455 or Rachel at 573-548-0394 for a local commercial insurance review. Randy Dinwiddie Licensed agent Holts Summit Mo 65043 ━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━ CONTINUE HOME ━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
- DealMaker Motors Jefferson City MO: Dealer-Free Private Party Trucks under $12,000
Focus Keyword: Dealer-Free Private Party Trucks Jefferson City MO 65043 URL Slug: dealer-free-private-party-trucks-jefferson-city-mo-65043 Category: DealMaker Motors (Cars) Excerpt: Find verified private-party trucks in Jefferson City and Holts Summit, Missouri, including a 2010 Ford F-150 4x4 listed under $12,000 with no dealer fees or doc fees. Tags: #DealMakerMotors #PrivatePartyTrucks #DealerFree #JeffersonCityMO #JeffersonCity65101 #JeffersonCity65109 #HoltsSummitMO #HoltsSummit65043 #ColeCountyMO #MidMissouriTrucks #UsedTrucksMissouri #FordF150Missouri #F1504x4 #TrucksUnder12000 #UsedTrucksJeffersonCity #NoDealerFees #NoDocFees #PrivatePartySale #ByOwnerTrucks #MissouriTruckShopping #ColumbiaMO #BooneCountyMO #FultonMO #LakeOzarkMO #OsageBeachMO #CamdentonMO #RussellvilleMO #EldonMO #VersaillesMO #VerifiedVehicleListings Search Terms: dealer-free private party trucks Jefferson City MO 65043 used trucks Jefferson City MO under 12000 private party trucks Holts Summit MO Ford F-150 4x4 for sale Jefferson City no dealer fee trucks Mid-Missouri used trucks for sale by owner Cole County affordable pickup trucks Jefferson City MO used trucks Columbia MO private seller verified private party vehicles Missouri used trucks near Holts Summit 65043 buy a truck direct from owner Missouri DealMaker Motors truck listings SEO Title: DealMaker Motors Jefferson City MO: Dealer-Free Private Party Trucks under $12,000Amerishop Services LLC SEO Advertisinghttps://static.prod-images.emergentagent.com/jobs/cd1f68a8-7def-4c58-8a0b-02d1733bca66/images/c6742005e3a255a39f3cb6135ef2477ffed87ff9be21ab3d58d595521e636f6e.jpeg SEO Description: Amerishop Services LLC SEO Advertising Find a verified private-party Ford F-150 4x4 listed at $9,995 near Jefferson City and Holts Summit, Missouri.https://static.prod-images.emergentagent.com/jobs/cd1f68a8-7def-4c58-8a0b-02d1733bca66/images/c6742005e3a255a39f3cb6135ef2477ffed87ff9be21ab3d58d595521e636f6e.jpeg og:site_name: Amerishop Services LLC SEO Advertising og:image:https://static.prod-images.emergentagent.com/jobs/cd1f68a8-7def-4c58-8a0b-02d1733bca66/images/c6742005e3a255a39f3cb6135ef2477ffed87ff9be21ab3d58d595521e636f6e.jpeg og:image:width: 1200 og:image:height: 630 Featured Image Alt Text: 2010 Ford F-150 Blackout SuperCrew 4x4 listed under $12,000 by DealMaker Motors in Jefferson City MO Geo Focus: Jefferson City, Missouri 65101 and 65109; Holts Summit, Missouri 65043; reference coordinates 38.57, -92.17; approximately 60-mile Mid-Missouri service area. 314-580-3455 | Dealer-Free Private Party Trucks Jefferson City MO 65043 | DealMaker Motors If you are searching for Dealer-Free Private Party Trucks Jefferson City MO 65043, you want more than a low advertised number. You want to know the actual price, the vehicle’s condition, the seller’s expectations, and whether unexpected fees will appear before you receive the keys. DealMaker Motors provides a private-party alternative for vehicle buyers in Jefferson City, Cole County, Holts Summit, Columbia, Boone County, and surrounding Mid-Missouri communities. The current official inventory includes a 2010 Ford F-150 Blackout SuperCrew 4x4 listed at $9,995, placing it below the $12,000 target for buyers who need pickup-truck capability without a new-truck payment. The listing is available through the current Amerishop Autos inventory, where you can review vehicle photos, pricing, available specifications, and individual listing information. You can also review the official vehicle inventory page from Dependable Brokers. Choice Summary: A private-party listing gives you a direct path to the seller, a posted price, and a clear opportunity to inspect the truck before purchase. Advantage Summary: When the listed price is $9,995, you can compare your total budget more easily because the advertised transaction does not add dealer fees or doc fees. 314-580-3455 | Dealer-Free Private Party Trucks Jefferson City MO 65043 | DealMaker Motors A capable F-150 below your $12,000 budget The featured truck is a 2010 Ford F-150 SuperCrew 4x4, a practical format for work, property maintenance, recreation, and family use. The SuperCrew cab provides four full doors and additional passenger space, while the 4x4 system can be useful for gravel roads, rural driveways, winter conditions, boat ramps, and job sites. The official inventory description identifies these key details: Vehicle: 2010 Ford F-150 Blackout SuperCrew 4x4 Listed price: $9,995 Engine: 5.4L Triton V8 Drivetrain: 4x4 Exterior: Tuxedo Black or Blackout styling as identified in the inventory materials Utility features: Spray-in bedliner and full tow package Location: Jefferson City, Missouri Transaction type: Private-party sale Fees advertised by DealMaker Motors: $0 dealer fee and $0 doc fee Would a 4x4 pickup, tow package, and spray-in bedliner meet your needs better than a smaller vehicle at the same price? If you need a truck for hauling equipment or occasional towing, those features can matter more than cosmetic upgrades. The listing is subject to availability, and you should confirm the price, title status, mileage, equipment, and condition directly before traveling. Used inventory can change quickly, especially when a truck is priced below $12,000. Choice Summary: Choose this F-150 if you value truck utility, passenger space, and four-wheel-drive capability within a sub-$12,000 vehicle budget. Advantage Summary: The private-party format lets you evaluate the truck directly instead of paying for dealership overhead through added transaction charges. 314-580-3455 | Dealer-Free Private Party Trucks Jefferson City MO 65043 | DealMaker Motors Know exactly what a private-party sale includes DealMaker Motors is presented as a private-party seller rather than a traditional motor vehicle dealership. That distinction matters because the process is different. There is no finance office, no in-house dealer financing, and no promise that a vehicle is covered by a dealership warranty. The inventory page states that: Buyers pay their own Missouri sales tax, title, and registration. Vehicles are sold as-is, where-is. Buyers should inspect the vehicle before purchasing. The seller does not finance vehicles directly. Outside financing may be available through third-party lenders, subject to lender approval and terms. The buyer should verify the title, vehicle identification number, odometer disclosure, lien status, and required Missouri paperwork before completing the transaction. You may also want to arrange a pre-purchase inspection with an independent mechanic. A mechanic can evaluate the engine, transmission, suspension, brakes, tires, frame, drivetrain, cooling system, and electronic systems. Missouri private-party vehicle transactions may involve state requirements addressed in statutes including RSMo § 301.550, RSMo § 301.570, RSMo § 144.020, and RSMo § 303.025. These references do not replace legal advice or instructions from the Missouri Department of Revenue. Confirm current title, registration, tax, insurance, and transfer requirements with the appropriate state office. AS IS WHERE IS DISCLAIMER: Every vehicle is sold as-is, where-is. Inspect before you buy. Buyer pays tax and title. DealMaker Motors does not provide a warranty unless a written agreement specifically states otherwise. Choice Summary: Choose a private-party transaction when you are prepared to inspect the vehicle, verify its documents, and accept responsibility for its condition after purchase. Advantage Summary: The process is transparent because you know in advance that tax, title, registration, financing, and inspection are separate buyer responsibilities. 314-580-3455 | Dealer-Free Private Party Trucks Jefferson City MO 65043 | DealMaker Motors A local option for Jefferson City and Holts Summit buyers The featured service area includes Jefferson City ZIP codes 65101 and 65109, as well as Holts Summit ZIP code 65043. DealMaker Motors also serves buyers searching around Columbia and Boone County, including ZIP codes 65201 and 65203, along with Fulton 65251, Russellville 65074, Eldon 65026, Versailles 65084, Lake Ozark 65049, Osage Beach 65065, Camdenton 65020, and Kingdom City 65262. That regional coverage is useful when you are comparing private-party trucks across Mid-Missouri. A truck located in Holts Summit may be a short drive from Jefferson City, while listings in Columbia, Fulton, or Lake Ozark could provide additional options if the first vehicle sells. Before arranging a showing, ask: Is the truck still available at the posted price? Is the title clear and available for transfer? Does the VIN match the title and listing? Are there known mechanical, frame, rust, or electrical concerns? Can you inspect and test-drive the vehicle by appointment? Can your mechanic inspect it before you purchase? What payment methods are accepted? Which documents will be provided at closing? Text 314-580-3455 to request an appointment. You may also contact Randy Dinwiddie at 314-580-3455 or Rachel at 573-548-0394. The inventory page indicates that serious buyers can often arrange a viewing within a day or two, depending on seller availability. Choice Summary: Choose a local Mid-Missouri listing when proximity makes it easier to inspect the truck, bring a mechanic, and complete the transaction carefully. Advantage Summary: Local access can save you time and travel expense while giving you a practical opportunity to evaluate the truck in person. 314-580-3455 | Dealer-Free Private Party Trucks Jefferson City MO 65043 | DealMaker Motors Compare the truck against your full transportation budget A $9,995 purchase price does not represent every cost of ownership. You should reserve money for Missouri sales tax, title and registration charges, insurance, fuel, maintenance, tires, and potential repairs. Older trucks may offer an attractive purchase price but can require more frequent service than a newer vehicle. Ask yourself what matters most: Do you need 4x4 for work or rural travel? Will you use the tow package often? Do you need a SuperCrew cab? Can your monthly budget support fuel and maintenance for a V8? Have you budgeted for a pre-purchase inspection? Would a smaller SUV or sedan meet your needs at a lower operating cost? The same current inventory includes other Mid-Missouri vehicles below or near the $12,000 range, including a 2011 Mercedes-Benz C300 listed at $7,500, a 2014 Cadillac SRX listed at $8,995, and a 2014 Mercedes-Benz ML350 listed at $10,450. These are not substitutes for a pickup truck, but they show why it is worth reviewing the complete inventory before making a decision. If truck capability is the priority, the F-150 is the clear match among the vehicles highlighted here. If passenger comfort, fuel costs, or lower initial spending matter more, another vehicle may fit your financial goals better. Choice Summary: Select the vehicle that fits your complete ownership budget, not only the number on the listing. Advantage Summary: Comparing several verified listings helps you make a decision based on use, condition, and total cost rather than urgency alone. 314-580-3455 | Dealer-Free Private Party Trucks Jefferson City MO 65043 | DealMaker Motors Schedule your inspection before the truck is sold The current 2010 Ford F-150 Blackout SuperCrew 4x4 is listed at $9,995, below the $12,000 target for buyers seeking a used truck in Jefferson City, Cole County, or Holts Summit. Because private-party inventory can change without notice, confirm availability before making travel plans. Start by reviewing the vehicle inventory on Amerishop Autos, then text 314-580-3455 to request an appointment. Bring your driver’s license, proof of insurance for a test drive if required, and the contact information for your mechanic. Do not send payment before you have inspected the vehicle, reviewed the documents, and agreed to the transaction terms. For broader company information, visit Dependable Brokers and review the Dependable Brokers vehicle inventory page. Dealer-Free Private Party Trucks Jefferson City MO 65043 gives you a straightforward way to compare local pickup options, verify the details yourself, and pursue a truck at a posted price without dealer or doc fees. The right choice is the vehicle that passes your inspection and supports your budget after tax, title, registration, insurance, fuel, and maintenance. Choice Summary: Schedule an inspection, verify the paperwork, and decide only after the truck meets your needs. Advantage Summary: Direct communication, clear pricing, and local access help you shop with more information and fewer surprises. Geo-Code Tags: Jefferson City, MO 65101; Jefferson City, MO 65109; Holts Summit, MO 65043; Columbia, MO 65201; Columbia, MO 65203; Fulton, MO 65251; Russellville, MO 65074; Eldon, MO 65026; Versailles, MO 65084; Lake Ozark, MO 65049; Osage Beach, MO 65065; Camdenton, MO 65020; Kingdom City, MO 65262; Cole County; Boone County; Mid-Missouri; approximately 60-mile radius from 38.57, -92.17. Contact: Randy Dinwiddie : 314-580-3455 | Rachel : 573-548-0394
- Fire Extinguisher Requirements for Missouri Businesses: Jefferson City and Mid-Missouri Compliance Guide
Focus Keyword: fire extinguisher requirements Missouri business URL Slug: fire-extinguisher-requirements-missouri-65101 Category: Amerishop Directory (Business) Excerpt: Practical Missouri fire extinguisher compliance guide for Jefferson City, Columbia, Cole County, and Boone County businesses covering Class A/B/C/D/K ratings, placement, inspection, maintenance, signage, training, and verified directory visibility. SEO Title: Fire Extinguisher Requirements for Missouri Businesses: Jefferson City and Mid-Missouri Compliance Guide https://cdn.marblism.com/8Tkpd1r3OJG.webp SEO Description: Missouri business fire extinguisher compliance guide covering ratings, placement, inspections, maintenance, training, and Mid-Missouri resources https://cdn.marblism.com/8Tkpd1r3OJG.webp og:site_name: Amerishop Directory og:image:https://cdn.marblism.com/8Tkpd1r3OJG.webp og:image:width: 1200 og:image:height: 630 Featured Image Alt Text: Fire extinguisher requirements for Missouri businesses in Jefferson City and Mid-Missouri Tags: Missouri fire safety, fire extinguisher requirements, Missouri business compliance, Jefferson City businesses, Columbia Missouri businesses, Cole County business, Boone County business, Mid-Missouri small business, Class A extinguisher, Class B extinguisher, Class C extinguisher, Class D extinguisher, Class K extinguisher, NFPA 10, OSHA 1910.157, fire extinguisher inspection, fire extinguisher maintenance, monthly fire safety checks, annual fire inspection, commercial kitchen safety, fire safety training, fire extinguisher placement, business insurance Missouri, general liability insurance, business directory Missouri, verified business listings, local SEO Missouri, Jefferson City 65101, Columbia 65201, Amerishop Directory Search Terms: fire extinguisher requirements Missouri business; Missouri commercial fire extinguisher rules; Jefferson City fire extinguisher inspection; Columbia MO business fire safety; Mid-Missouri fire code compliance; 2A-10B:C extinguisher 75 feet; Class K extinguisher Missouri restaurant; OSHA 1910.157 extinguisher inspection; NFPA 10 annual maintenance Missouri; fire safety training for employees Missouri; Cole County business compliance; Boone County business directory 314-580-3455 | fire extinguisher requirements Missouri business | Amerishop Directory If you operate a restaurant, retail store, office, warehouse, service company, or other small business in Jefferson City, Columbia, Cole County, or Boone County, fire extinguisher compliance is part of protecting your employees, customers, property, and operating investment. What does compliance actually require? Which extinguisher rating belongs in your facility? How far can an employee travel to reach one? And are monthly checks enough? Missouri does not have one universal statewide fire code for every commercial property. The Missouri Division of Fire Safety explains that fire and building codes are generally adopted and enforced locally. Some licensed occupancies, including certain care facilities, also have additional state requirements. For most businesses, local code adoption, the International Fire Code, NFPA 10, and OSHA requirements may all affect your responsibilities. The first step is confirming the requirements enforced by your local authority having jurisdiction, or AHJ. The Missouri Division of Fire Safety FAQ is a useful starting point, but your local fire department or code official should confirm the rules for your specific building and occupancy. Advantage: A documented, location-specific review is more reliable than assuming that the same extinguisher plan applies to every Missouri business. 314-580-3455 | fire extinguisher requirements Missouri business | Amerishop Directory 314-580-3455 | fire extinguisher requirements Missouri business | Amerishop Directory Match the extinguisher to the hazard Fire extinguishers are classified according to the type of fire they are designed to control: Class A: Wood, paper, cloth, cardboard, and other ordinary combustibles. Class B: Gasoline, oils, solvents, grease, and other flammable liquids. Class C: Energized electrical equipment. Class D: Combustible metals such as magnesium or titanium. Class K: Cooking oils and fats in commercial kitchens. For many ordinary commercial spaces, the Missouri Division of Fire Safety identifies an ABC-rated extinguisher as the general choice, with a minimum rating of 2A-10B:C. This type provides coverage for ordinary combustibles, flammable liquids, and energized electrical equipment. A restaurant or commercial food operation may need more than a general ABC extinguisher. A Class K extinguisher is designed for cooking oil and fat hazards and should be located near commercial cooking equipment. Depending on the kitchen, an automatic hood suppression system may also be required. A machine shop, fabrication business, or industrial operation may require a Class D extinguisher after a hazard assessment. Class D units are not a substitute for ABC coverage throughout the building. Choice: Select equipment based on the materials, machinery, cooking processes, and chemicals present: not simply the size of the building. 314-580-3455 | fire extinguisher requirements Missouri business | Amerishop Directory Place units within practical travel distance The Missouri Division of Fire Safety states that commercial buildings generally need at least one 2A-10B:C extinguisher within 75 feet of all points in the building. Stairs cannot be used as the travel path to reach an extinguisher. The same guidance states that one 2A-10B:C extinguisher can typically serve a maximum of approximately 3,000 square feet, although some operations require more extensive coverage. A practical placement review should consider: At least one extinguisher on each floor when required by the applicable code. Maximum travel distance of approximately 75 feet on the same floor. Extra units near kitchens, break rooms, storage areas, furnace rooms, electrical rooms, and mechanical spaces. Clear visibility and unobstructed access. Placement on approved brackets or in cabinets. Locations away from elevator hoistways, pits, and car tops. Additional coverage for flammable-liquid storage or special industrial hazards. Missouri state office specifications provide a useful benchmark by calling for at least two five-pound ABC extinguishers, with additional units when travel distance exceeds 75 feet. That specification applies to state facilities and is not automatically the rule for every private business, but it demonstrates why a simple “one extinguisher per building” approach may be inadequate. If your business has been remodeled, expanded, divided into suites, or moved into a different occupancy classification, reassess the layout. A previously acceptable placement may no longer provide the necessary coverage. Advantage: Correct placement helps employees locate protection quickly while giving your fire inspector a clear, defensible compliance plan. 314-580-3455 | fire extinguisher requirements Missouri business | Amerishop Directory Build a monthly and annual inspection system Under OSHA 29 CFR 1910.157, employers must provide monthly visual inspections and annual maintenance when portable extinguishers are provided for employee use. OSHA’s portable fire extinguisher standard also addresses employee education, hands-on training, and hydrostatic testing. During a monthly visual check, a trained staff member should confirm that: The extinguisher is in its designated location. The gauge indicates an acceptable charge. The pin and tamper seal are intact. The hose or nozzle is not blocked. The cylinder has no obvious damage, leakage, or corrosion. The unit is visible, accessible, and properly mounted. The inspection date and initials are recorded. Annual maintenance is more thorough. A qualified fire-protection technician should examine the unit, service it as necessary, apply the appropriate inspection tag, and provide documentation. The State of Missouri’s office specifications require annual inspection and maintenance by trained personnel, signed records, and a replacement extinguisher of equal or greater rating whenever a unit is removed for service or recharge. Long-cycle service may also apply. Depending on the extinguisher type, OSHA and NFPA 10-based programs can involve internal examination periods, such as six-year maintenance for certain dry-chemical units, and hydrostatic testing at prescribed intervals. Confirm the schedule with your qualified service provider. Choice: Monthly staff checks identify obvious problems; annual professional maintenance verifies whether the extinguisher can operate effectively. 314-580-3455 | fire extinguisher requirements Missouri business | Amerishop Directory Train employees and keep records OSHA requires employee education when portable extinguishers are provided for employee use. Training should explain the general principles of extinguisher operation and the hazards of attempting to fight an incipient-stage fire. If employees are expected to use extinguishers, provide training on: When to evacuate instead of attempting fire suppression. How to activate the alarm and call 911. The PASS method: pull, aim, squeeze, and sweep. The correct extinguisher for the hazard. Escape routes and backup exits. The importance of keeping a clear exit behind the person using the extinguisher. Training should occur during initial employment and at least annually under OSHA’s employee education requirements. Keep attendance records with the date, trainer, subjects covered, and participating employees. Some Missouri licensed facilities have stricter requirements. For example, Missouri residential care and assisted living regulations require training during orientation and at least every six months. Those rules do not automatically apply to a general office or retail store, but they show why occupancy type matters. Advantage: Written inspection and training records demonstrate that fire safety is an active management process: not a one-time purchase. 314-580-3455 | fire extinguisher requirements Missouri business | Amerishop Directory Verify your Mid-Missouri compliance location Use your exact business address when confirming local requirements. The following map and latitude-longitude references identify the primary service area for this guide: Jefferson City, 65101: 38.57, -92.17 Holts Summit, 65043: 38.63, -92.12 Columbia, 65201: 38.95, -92.33 Fulton, 65251: 38.85, -91.95 Ashland, 65010: 38.77, -92.26 These communities fall within the hyper-local Mid-Missouri coverage area for this business-focused resource. Contact the relevant city fire department, county authority, building official, or state licensing agency for the rules that apply to your occupancy. Your insurance program should also reflect your actual operations. Dependable Brokers offers business directory advertising, business insurance guidance, commercial coverage, and general liability resources for Mid-Missouri owners. Fire prevention documentation can support responsible risk management, although it does not replace a policy review or guarantee a specific insurance outcome. For quick assistance, contact Randy Dinwiddie at 314-580-3455 or Rachel at 573-548-0394. 30-day directory renewal red line: Contact 314 5803455 to renew before your verified directory visibility expires. A verified listing can help customers find your business by service and location, whether they are searching in Jefferson City, Columbia, Cole County, Boone County, Holts Summit, Fulton, or Ashland. Keep your business name, phone number, address, operating hours, service description, and safety-related credentials accurate. Choice: Protect the building, document compliance, review your coverage, and maintain accurate directory visibility before an urgent inspection or customer search creates pressure. 314-580-3455 | fire extinguisher requirements Missouri business | Amerishop Directory Final compliance checklist Before your next inspection or annual service appointment, confirm that you have: Verified the applicable local fire-code requirements. Identified Class A, B, C, D, and K hazards in your facility. Installed properly rated extinguishers, including at least 2A-10B:C ABC units where applicable. Kept travel distance within the applicable 75-foot requirement. Provided Class K protection for commercial cooking hazards when required. Kept extinguishers visible, accessible, mounted, and signed. Completed and documented monthly visual checks. Scheduled annual maintenance by qualified personnel. Tracked six-year and hydrostatic-testing milestones when applicable. Trained employees and retained attendance records. Replaced units with equal or greater protection during service. Confirmed your local AHJ’s requirements after renovations or changes in occupancy. Fire extinguisher requirements for a Missouri business depend on the building, hazards, employees, customers, licensing status, and local code adoption. Use this guide as an operational starting point, then confirm the final requirements with your local fire authority and qualified fire-protection professional. #MissouriBusiness #MissouriFireSafety #FireExtinguisherRequirements #JeffersonCityMO #ColumbiaMO #MidMissouriBusiness #ColeCounty #BooneCounty #HoltsSummit #FultonMO #AshlandMO #NFPA10 #OSHA1910157 #ClassAExtinguisher #ClassBExtinguisher #ClassCExtinguisher #ClassDExtinguisher #ClassKExtinguisher #CommercialKitchenSafety #FireInspection #FireExtinguisherMaintenance #FireSafetyTraining #BusinessCompliance #SmallBusinessMissouri #GeneralLiabilityInsurance #BusinessInsuranceMissouri #VerifiedBusinessListings #LocalSEOMissouri #AmerishopDirectory #RandyDinwiddie
- Fire Safety for Restaurants Mid-Missouri: Inspections, Suppression Systems, and Verified Directory Listings
status: Draft for transfer to Emergent focus_keyword: fire safety for restaurants Mid-Missouri url_slug: fire-safety-restaurants-mid-missouri-65101 category: Amerishop Directory (Business) excerpt: A practical guide to fire safety for restaurants Mid-Missouri, including kitchen suppression systems, hood cleaning, Class K and ABC extinguishers, inspections, evacuation planning, and verified local directory listings. tags: - fire safety for restaurants Mid-Missouri - restaurant fire inspections Missouri - commercial kitchen suppression systems - hood cleaning Jefferson City - Class K fire extinguisher - ABC fire extinguisher - UL 300 kitchen suppression - restaurant safety Columbia MO - Cole County fire safety - Boone County fire safety - Jefferson City restaurant safety - Holts Summit business directory - Fulton Missouri restaurant safety - Ashland Missouri business listings - smoke alarms restaurant - restaurant evacuation plan - fire protection providers Mid-Missouri - Amerishop Directory - verified business listings Missouri - local SEO for restaurants - restaurant insurance Missouri - commercial general liability - business interruption coverage - kitchen fire prevention - fire marshal inspection checklist - #1 used cars Jeff City - #1 private party - Randy Dinwiddie - Rachel 573-548-0394 - Mid-Missouri business directory search_terms: - fire safety for restaurants Mid-Missouri - restaurant fire inspection Jefferson City MO - commercial kitchen suppression Columbia Missouri - Class K extinguisher restaurant Missouri - ABC fire extinguisher restaurant requirements - hood cleaning Cole County restaurants - Boone County restaurant fire protection - UL 300 suppression system Mid-Missouri - restaurant evacuation plan Missouri - fire protection provider Holts Summit MO - verified restaurant directory Mid-Missouri - Amerishop Directory restaurant listing invisible_keywords: "#1 used cars Jeff city; #1 private party" seo_title: Fire Safety for Restaurants Mid-Missouri: Inspections, Suppression Systems, and Verified Directory Listings seo_description: Learn the practical requirements for fire safety for restaurants Mid-Missouri, including suppression systems, hood cleaning, extinguishers, inspections, evacuation plans, and local directory visibility. og:site_name: Amerishop Directory og:image: https://cdn.marblism.com/M-pmVGNpOTz.webp og:image:width: 1200 og:image:height: 630 featured_image_alt: Commercial kitchen hood, suppression nozzles, and fire extinguisher representing fire safety for restaurants Mid-Missouri Draft for transfer to Emergent. This article is intended for restaurants, food-service operators, and fire-protection providers serving Mid-Missouri. 314-580-3455 | fire safety for restaurants Mid-Missouri | Amerishop Directory Running a restaurant in Jefferson City, Columbia, Cole County, or Boone County means managing more than food, staffing, and customer service. You are also responsible for protecting employees, guests, equipment, inventory, and the building from preventable fire hazards. What would happen if grease accumulated inside your hood and ductwork? Are your suppression nozzles positioned for your current cooking equipment? Can your staff identify the difference between a Class K extinguisher and an ABC extinguisher? These are practical questions for every restaurant owner. Fire safety for restaurants Mid-Missouri should be treated as an ongoing operating system: not a one-time checklist completed only before an inspection. Local requirements can vary by municipality, fire district, building type, occupancy, and authority having jurisdiction. Always confirm current requirements with your local fire marshal and qualified fire-protection contractor. Advantage: A documented, recurring safety program helps you reduce hazards, prepare for inspections, and protect your financial investment. 314-580-3455 | fire safety for restaurants Mid-Missouri | Amerishop Directory Protect the cooking line with a properly maintained suppression system Most grease-producing commercial cooking operations require a Type I hood and an automatic wet-chemical suppression system designed for kitchen fires. Many current systems are built around UL 300 performance standards, but the correct system depends on the appliances, fuel sources, hood configuration, and local approval requirements. A qualified technician should verify that: Nozzles cover each fryer, griddle, range, broiler, or other protected appliance. The hood, plenum, and duct areas are properly covered. The manual pull station is accessible and clearly identified. Gas and electrical fuel shutoffs activate correctly. Fusible links, detection lines, cylinders, gauges, and interlocks are in serviceable condition. Nozzle caps are clean and correctly installed. Service records and deficiency reports are available for review. Commercial kitchen suppression systems are commonly inspected every six months. A new appliance, hood modification, menu change, or kitchen remodel may require an additional review because equipment changes can affect nozzle placement and system coverage. Korsmeyer Fire Protection lists restaurant suppression installation, maintenance, and mandatory semi-annual inspections among its Mid-Missouri services. Its published address is 5007 Buffalo Road, Jefferson City, MO 65101, with phone service at 573-659-8805. You can review its restaurant fire suppression information and contact the company directly to confirm service availability. Choice: Select a system and maintenance schedule based on your actual appliances: not a generic package that may not match your kitchen. Keep hood cleaning documentation current Grease buildup is fuel. It can also obstruct airflow, contaminate system components, and increase the severity of a kitchen fire. Cleaning frequency should reflect how your restaurant operates: Monthly: High-volume, 24-hour, fast-food, or solid-fuel cooking operations. Quarterly: High-volume kitchens and operations with heavy grease production. Semi-annually: Many average-volume, sit-down restaurants. Annually: Low-volume or seasonal operations when permitted by local requirements. Some fire-prevention checklists specifically call for hood and duct cleaning and tagging every six months. The cleaning tag should identify the service date and contractor. Keep invoices, photographs, certificates, and deficiency corrections with your fire-safety records. Advantage: A recurring hood-cleaning calendar gives you evidence of maintenance and makes it easier to prepare before an inspection notice arrives. 314-580-3455 | fire safety for restaurants Mid-Missouri | Amerishop Directory Use the right extinguisher in the right location A Class K extinguisher is designed for fires involving cooking oils and fats. It belongs near commercial cooking appliances and must remain accessible: not hidden behind boxes, shelving, or stored equipment. ABC extinguishers are generally used in dining areas, storage rooms, offices, and other locations where ordinary combustibles, flammable liquids, or energized electrical equipment may be involved. Your restaurant should confirm: Class K extinguishers are located near grease-producing appliances. ABC extinguishers are placed throughout non-kitchen areas. Extinguishers are mounted, visible, accessible, and not blocked. Pressure gauges, pins, seals, hoses, and cylinders appear serviceable. Annual service is completed by a qualified or licensed technician where required. Employees understand when to use an extinguisher and when to activate the suppression system, evacuate, and call 911. An extinguisher is not a substitute for evacuation or automatic suppression. If a fire is spreading, producing heavy smoke, or blocking an exit, your priority is to activate the alarm, notify others, leave the building, and contact emergency services. Choice: Use Class K protection for cooking-oil hazards and ABC protection for general areas, while training staff to avoid taking unnecessary risks. Prepare for the inspection beyond the kitchen Restaurant fire inspections can include the exterior, interior, exits, alarms, sprinklers, kitchen systems, and administrative records. A practical inspection file should include: Visible street numbers and rear-door identification. Clear access to hydrants, fire department connections, gas meters, and electrical service. Functional exit signs with battery backup. Emergency lighting that operates during power loss. Clear exit routes and properly functioning exit doors. Posted evacuation plans when required. Smoke alarms and fire alarm systems without trouble signals. Annual alarm service documentation from a qualified technician. Sprinkler valves open or supervised, with adequate head clearance. Current suppression, hood-cleaning, extinguisher, and sprinkler records. Updated emergency contact names and phone numbers. Posted use permits or other required administrative documents. The Eureka Fire Protection District commercial fire-prevention checklist provides a useful example of the categories fire officials may examine. It identifies exterior access, exits, fire extinguishers, sprinkler systems, kitchen equipment, suppression systems, and emergency contacts as important inspection areas. Advantage: Organizing records in one accessible file can shorten the inspection process and help you address deficiencies quickly. 314-580-3455 | fire safety for restaurants Mid-Missouri | Amerishop Directory Build a location-specific emergency plan Your evacuation plan should reflect your actual floor plan, seating arrangement, kitchen exits, storage areas, and assembly location. Employees should know at least two exit routes when available, how to report a fire, where the manual pull station is located, and how to assist guests without creating additional danger. Include clear procedures for: Calling 911 and giving the restaurant’s exact address. Activating the fire alarm or suppression system. Shutting down equipment only when it can be done safely. Directing guests away from smoke and blocked exits. Meeting at a designated outdoor assembly point. Reporting missing employees or guests to responding firefighters. Avoiding re-entry until emergency officials provide authorization. For restaurant owners across the region, useful location references include: Jefferson City: ZIP 65101; approximately 38.57, -92.17. Holts Summit: ZIP 65043; approximately 38.63, -92.12. Columbia: ZIP 65201; approximately 38.95, -92.33. Fulton: ZIP 65251. Ashland: ZIP 65010. These communities fall within the requested Mid-Missouri service radius for this directory post. Use Google Maps restaurant fire-protection directions as a starting reference, then confirm the provider’s service area, arrival time, licensing, inspection credentials, and emergency availability. Mid Missouri Fire Protection lists installation, repair, maintenance, and inspection services and publishes 573-345-3997 as its contact number. You can also review its Mid Missouri Fire Protection website for current service details. Choice: Create one plan for your Jefferson City, Columbia, or surrounding location, then train every shift: not only managers. 314-580-3455 | fire safety for restaurants Mid-Missouri | Amerishop Directory Help local customers and providers find the right information Fire safety is operational protection, but visibility is also important. A restaurant searching for hood cleaning, extinguisher service, suppression inspections, or commercial insurance needs accurate local information. A fire-protection provider needs a clear way to reach restaurant owners in Jefferson City, Columbia, Holts Summit, Fulton, Ashland, Cole County, and Boone County. An Amerishop Directory listing can help organize essential business information such as: Business name and service category. Address and service radius. Phone number and contact person. Website and directions reference. Restaurant suppression, extinguisher, inspection, or hood-cleaning services. Hours, emergency availability, and appointment instructions. Verified local details that customers can review before calling. The Amerishop business directory advertising service states a $419 price for building a creative deal advertisement and online directory listing, with a six-month listing period. Changes before the end of that six-month contract are listed at $299. Confirm current terms before purchasing. 30-day red-line renewal notice: There are 30 days until deletion. Contact 314 5803455 to renew your listing. For assistance, ask for Randy at 314-580-3455 or Rachel at 573-548-0394. A verified listing does not replace fire-code compliance, a licensed inspection, or emergency planning. It does give your business a more accessible local presence when customers are looking for legitimate services and current contact information. Advantage: Combine documented safety practices with accurate local visibility so customers can find your restaurant or fire-protection business when timing matters. 314-580-3455 | fire safety for restaurants Mid-Missouri | Amerishop Directory Fire safety for restaurants Mid-Missouri starts with the basics: maintain a properly designed suppression system, clean hood and ductwork on schedule, service Class K and ABC extinguishers, test alarms and emergency lighting, keep exits clear, and train employees to evacuate safely. Then make your records and business information easy to verify. Whether you operate near 65101 in Jefferson City, 65043 in Holts Summit, 65201 in Columbia, Fulton, Ashland, Cole County, or Boone County, a clear inspection file and current directory listing can support better decisions. You can also review restaurant insurance information for Mid-Missouri food businesses and explore the restaurant and take-out directory category. Final Choice: Do not wait for a failed inspection, expired service tag, or deleted listing to create an avoidable problem. Schedule your next six-month suppression and hood-cleaning review, verify your evacuation plan, and renew your local directory listing before the 30-day deletion deadline. #FireSafetyRestaurantsMidMissouri #RestaurantFireSafety #MidMissouriRestaurants #JeffersonCityMO #ColumbiaMO #ColeCounty #BooneCounty #HoltsSummit #FultonMO #AshlandMO #KitchenSuppression #UL300 #HoodCleaning #ClassKExtinguisher #ABCExtinguisher #FireInspections #RestaurantSafety #FireProtection #EvacuationPlan #SmokeAlarms #EmergencyLighting #AmerishopDirectory #VerifiedListings #LocalBusinessDirectory #RestaurantInsurance #CommercialKitchen #FirePrevention #RandyDinwiddie #Rachel5735480394 #MidMissouriBusiness #FireSafetyRestaurantsMidMissouri #RestaurantFireSafety #MidMissouriRestaurants #JeffersonCityMO #ColumbiaMO #ColeCounty #BooneCounty #HoltsSummit #FultonMO #AshlandMO #KitchenSuppression #UL300 #HoodCleaning #ClassKExtinguisher #ABC extinguisher #FireInspections #RestaurantSafety #FireProtection #EvacuationPlan #SmokeAlarms #EmergencyLighting #AmerishopDirectory #VerifiedListings #LocalBusinessDirectory #RestaurantInsurance #CommercialKitchen #FirePrevention #RandyDinwiddie #Rachel5735480394 #MidMissouriBusinessWinvalid